Estimate Time12 min

Retirement planning checklist

Key takeaways

  • If you're saving for retirement, the best way to help ensure success is by saving consistently (Fidelity suggests saving 15% of your income annually, including any match you get from your employer) and investing appropriately for your age.
  • Consider using as many tax-advantaged accounts as possible to help boost your readiness for retirement, such as a 401(k), an IRA, and a health savings account (HSA).
  • Think about ways to keep pace with inflation and control health care costs, as well as sources of predictable income such as Social Security, a pension, or an income annuity to cover essential expenses.

Knowing how to plan for retirement can help turn a distant goal into a realistic plan. From setting savings targets and choosing tax-advantaged accounts to building future income, these steps can help you prepare for the years ahead, no matter where you are on your financial journey.

How to plan for retirement at every age

Having a vision can help you set a concrete goal for retirement. Once you’ve considered how you want to spend your time and where you want to live, you’ll have a better sense of what your retirement could cost. Your estimated expenses in retirement and how many years your savings will need to provide income will help you set your savings goal.

Consider these questions to start visualizing yourself in retirement.

  • What are you retiring to?
  • What do you want to do in retirement?
  • How does retirement fit in with the rest of your goals?
  • Are you on track to hit your retirement goals?

Read Viewpoints: Boost your odds of a successful retirement

Retirement planning in your 20s

Focus on saving as much as you can in tax-advantaged accounts and investing for growth potential.

How much should you have saved for retirement in your 20s? Aim to save an amount equal to your annual salary by age 30.1 To learn more about Fidelity's savings factors, read: How much do I need to retire?

Take advantage of time and the potential of compounding growth. When it comes to long-term saving, time can be one of your greatest advantages. The earlier you begin saving and investing, the lower your savings rate can be throughout your career thanks to the power of compounding.

Saving for retirement in your 20s can potentially compound over time
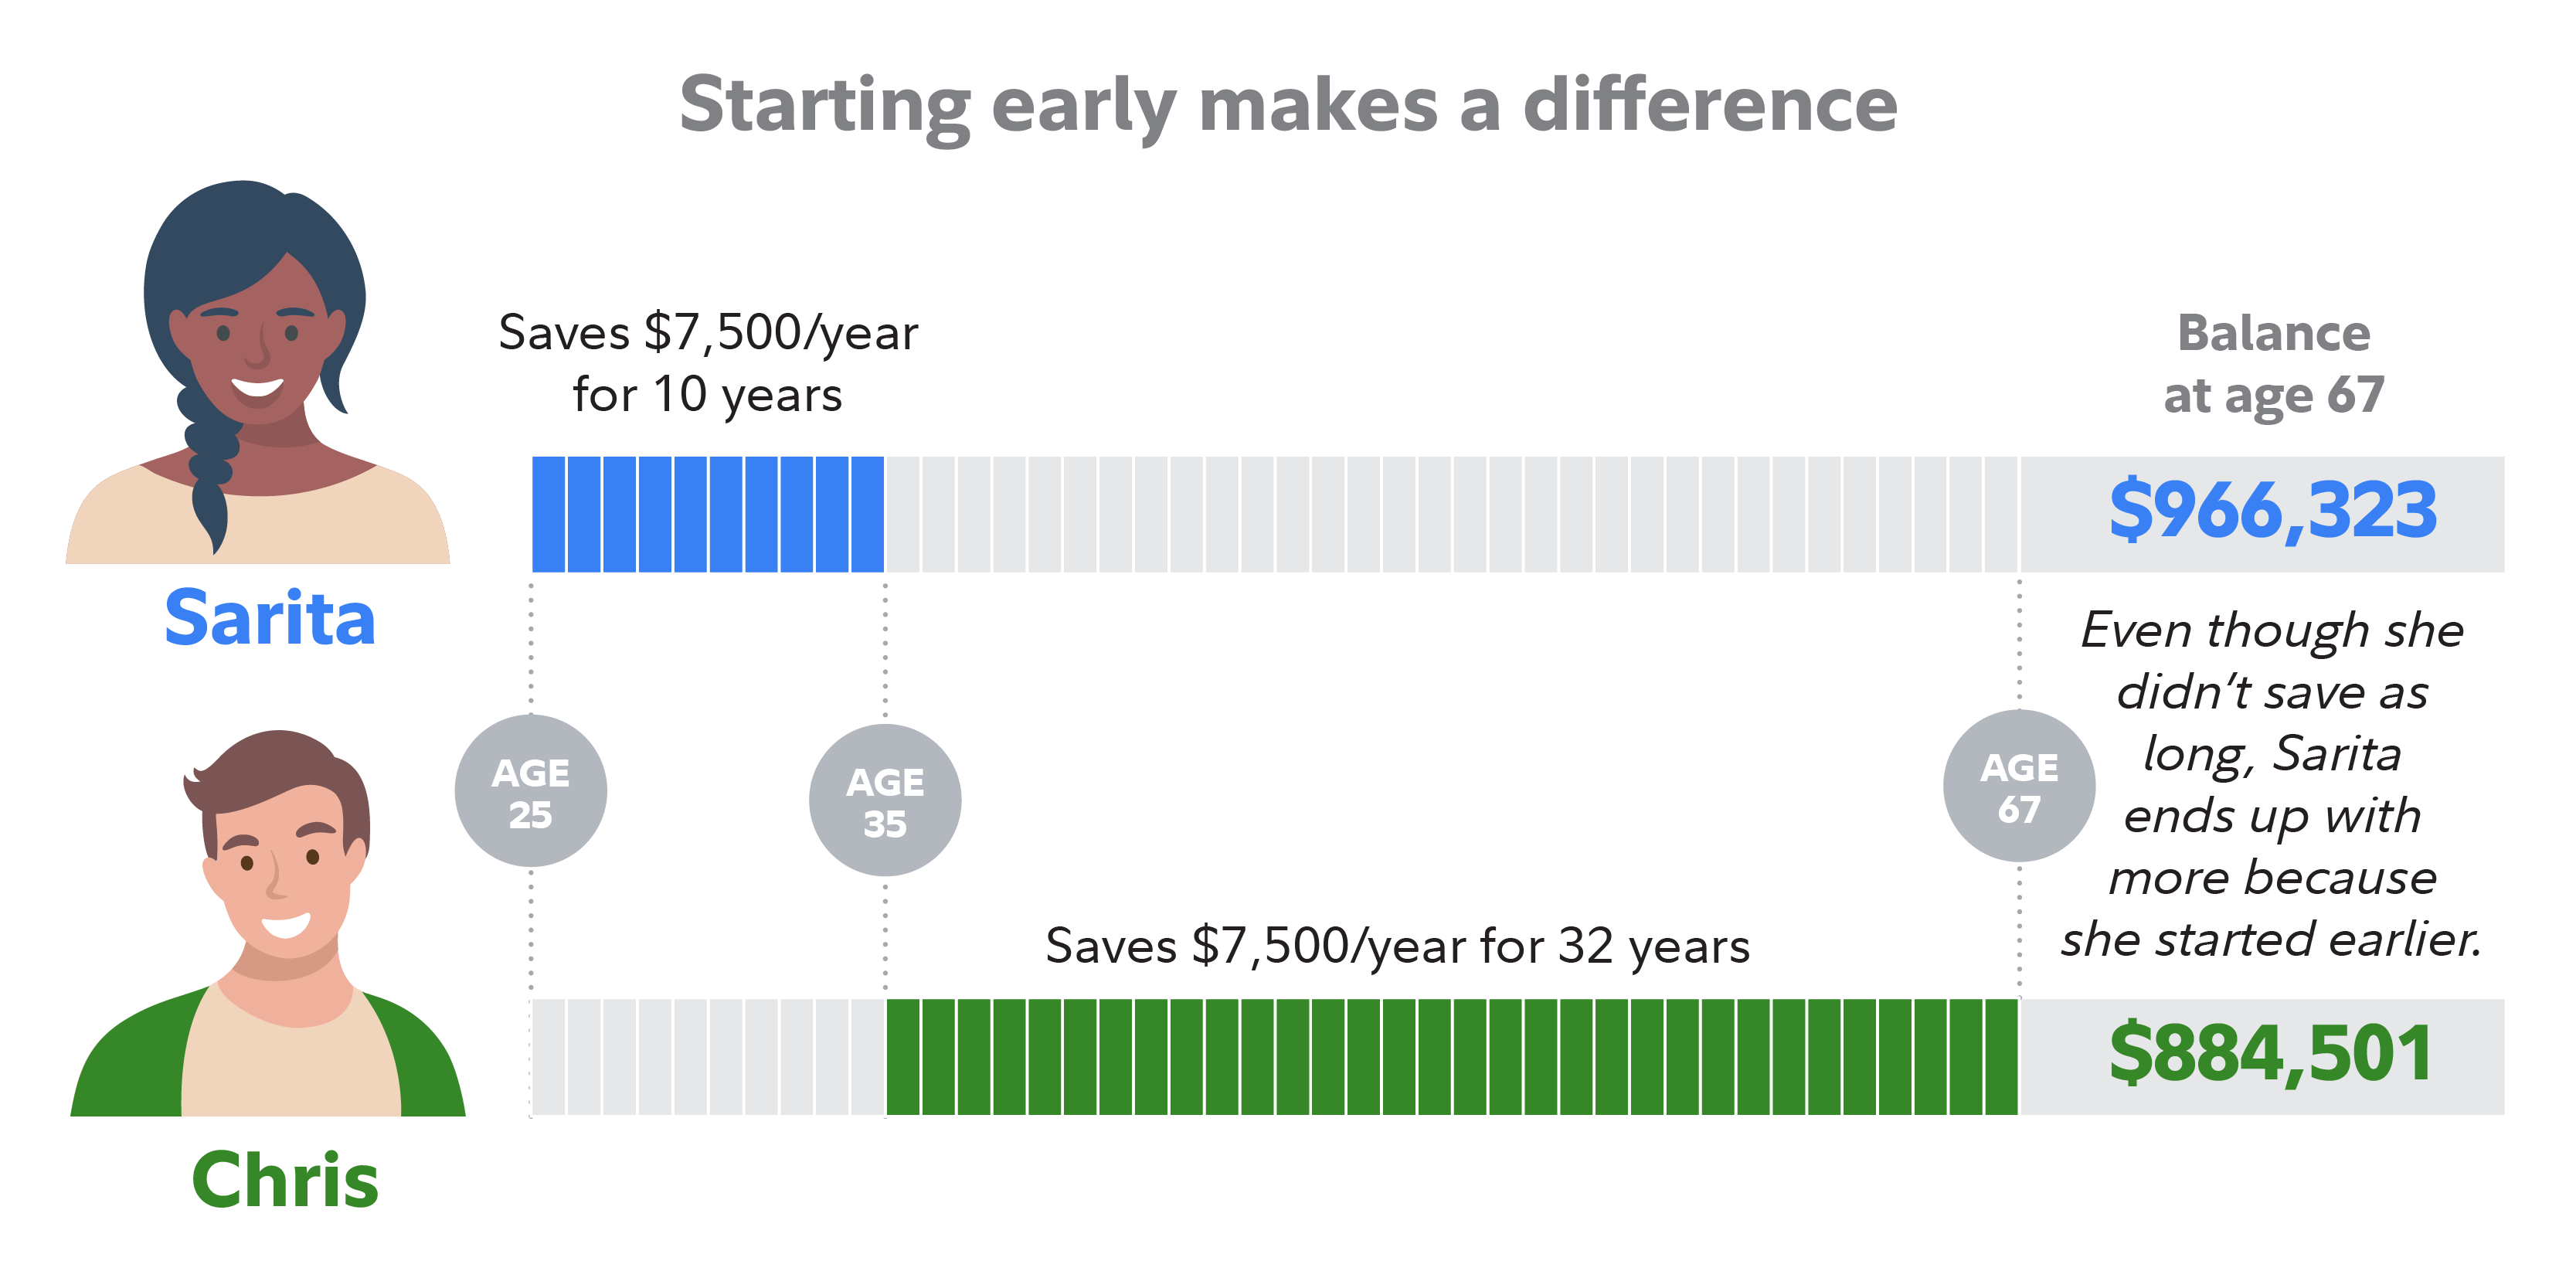
Starting early makes a difference when you're planning for retirement. Saving for 10 years starting at age 25 results in a higher balance than saving for 32 years starting at age 35.
This hypothetical example assumes the following: (1) annual IRA contributions on January 1 of each year for the age ranges shown with no withdrawals through age 67, (2) an annual $7,500 contribution for the first year and no catch-up contributions considered throughout the horizon, (3) an annual nominal rate of return of 7%, and (4) no taxes on any earnings within the IRA. The ending values do not reflect taxes, fees, or inflation. If they did, amounts would be lower. Earnings and pre-tax (deductible) contributions from traditional IRAs are subject to taxes when withdrawn. Earnings distributed from Roth IRAs are income tax-free provided certain requirements are met. IRA distributions before age 59½ may also be subject to a 10% penalty. Systematic investing does not ensure a profit and does not protect against loss in a declining market. This example is for illustrative purposes only and does not represent the performance of any security. Consider your current and anticipated investment horizon when making an investment decision, as the illustration may not reflect this. The assumed rate of return used in this example is not guaranteed. Investments that have potential for a 7% annual nominal rate of return also come with risk of loss.

Make the most of savings with tax-advantaged accounts. At this life stage, money can be scarce, but saving and investing what you can in a tax-advantaged account will pay off later in life. After all, the less you pay in taxes, the more potential you have to grow that money. Examples of tax-advantaged accounts include:

  • IRAs
  • Workplace savings plans like 401(k)s or 403(b)s
  • Health savings accounts (HSAs)

Your HSA, if you have one, can be a particularly powerful savings vehicle for retirement due to its triple tax advantage: Contributions are made on a pre-tax basis, or you may be able to deduct contributions you make outside of payroll, investments in the account have tax-free growth potential, and withdrawals are tax-free when used for qualified medical expenses now or in retirement.2

Read Viewpoints: 5 ways HSAs can help with your retirement

Decide how much you can save for retirement: Fidelity suggests saving 15% of your income annually, including any match you get from your employer. This assumes you start saving at age 25 and plan to retire at age 67.3

If 15% is too much, start where you can. If you get a match from your employer, aim to contribute enough to get the entire match and then increase your contribution rate each year until you get to 15%.

Investing for long-term growth potential. Over the long term, stocks have historically had higher returns than bonds or cash. In your 20s, consider investing in a diversified mix of investments with a significant portion devoted to stocks. Investors with many years before retirement have time to ride out the ups and downs in the market, and the potential compounding and growth that stocks can provide may help you reach your retirement goals. But balancing the growth potential of stocks with your own ability to tolerate risk is critical to staying invested for the long term.

Diversification, or spreading your investing dollars across several types of investments (generally stocks, bonds, and short-term investments), may not boost performance—it won’t ensure gains or guarantee against losses—but it has the potential to improve returns for the level of risk you’re targeting.

How does it do that? By possibly smoothing out the ride and providing some cushion against the big swings that can happen in the stock market. As you approach retirement, it can be a good idea to reduce the percentage of your portfolio invested in stocks and increase the percentage invested in bonds and short-term investments.

Another way to diversify when you’re investing for retirement could be with a target date fund. Target date funds provide a diversified mix of investments in one fund that gradually shifts to a more conservative mix as the target date nears, and beyond.

Learn about Fidelity's target date funds, Fidelity Freedom® Funds.

Read Viewpoints: Investing ideas for your IRA

Retirement planning in your 30s and 40s

Focus on amping up savings in tax-advantaged accounts and continuing to invest for long-term growth potential.

How much should you have saved for retirement in your 30s and 40s? Aim to save 3 times (3x) your annual salary by age 40 and 4x by age 45.1

Here are some tips that can help you work toward those savings goals.

  • Try to ramp up your savings. This is a busy time of life for many people, but it's also a time when your income may be on the rise. If you're not saving as much as you'd like or may need, try increasing your contributions each year when you can. For example, if you get a bonus or a raise, consider dedicating at least a part of it to retirement savings.
  • Find more tax-advantaged ways to save. Try to save as much as you can in tax-advantaged accounts like a 401(k), IRA, and HSA.

    If your company offers stock options or nonqualified deferred compensation plans, they could also be a way to help supercharge your savings if you've maxed out your other retirement accounts.

    Read Viewpoints on Fidelity.com: Make the most of company stock in your 401(k) and The basics of nonqualified deferred compensation

  • Consider a Roth conversion if it makes sense for your situation. If most of your retirement savings is held in traditional pretax accounts, such as IRAs and 401(k)s, it can sometimes make sense to convert some of the money into a Roth IRA and/or Roth 401(k). Years when your income is lower may be a good time to consider a conversion because the converted amount is generally subject to income taxes. But qualified withdrawals in retirement are tax-free, giving you more flexibility to reduce your overall tax bill in retirement. There are many considerations before doing a Roth conversion, including your current and future tax brackets.

    Read Viewpoints: Do you earn too much for a Roth IRA? and Backdoor Roth IRA: Is it right for you?

    It's best to speak with a tax professional to understand if and when this strategy could be good for you.

  • Continue investing for potential long-term growth. With a decade or more before you are likely to retire, you may want to keep the majority of your retirement portfolio in a diversified stock portfolio.
  • To learn more, read Viewpoints: Retirement playbook: What to consider in your 40s

Retirement planning in your 50s and 60s

Focus on catching up with savings, diversifying investments, and considering retirement income.

How much should you have saved for retirement in your 50s? Aim to save 6 times (6x) your annual salary by age 50 and 8x by age 60.1

Use catch-up contributions. People age 50 and older can take advantage of catch-up contributions to their retirement accounts, such as IRAs, HSAs, and 401(k)s.

To learn more, read Viewpoints: Retirement playbook: What to consider in your 50s

Diversify your investments. As you approach retirement, you may want to add more stability to your portfolio by balancing stocks’ long-term growth potential with the income and relative stability that bonds can provide. Your investment mix should continue to reflect your goals, time horizon, financial situation, and risk tolerance.

How much should you have saved for retirement by age 67? Aim to save 10 times (10x) your annual salary by age 67 if that is the age you plan to retire.1

To learn more, read Viewpoints: Retirement playbook: What to consider in your 60s

Contribution limits on tax-advantaged accounts

The contribution limits for tax-advantaged accounts are indexed to inflation and may be adjusted annually.

IRA contribution limits

The annual contribution limit for IRAs, including Roth and traditional IRAs, is $7,500 for 2026. If you're age 50 or older, you can contribute an additional $1,100 for 2026.

HSA contribution limits

For 2026, the IRS contribution limit for a health savings account (HSA) is $4,400 if you have individual health coverage, and $8,750 if you have family coverage, in an HSA-eligible health plan. The HSA contribution limits for 2027 are $4,500 for individual coverage and $9,000 for family coverage. Any employer contributions will count toward these limits.

If you're 55 or older during the tax year, you may be able to make a catch-up contribution, up to $1,000 per year. Your spouse, if age 55 or older, could also make a catch-up contribution, but will need to open their own HSA. See IRS Publication 969 for more on annual HSA contribution limits.

401(k) contribution limits

In 2026, you can contribute up to $24,500 pre-tax or Roth to your 401(k). Some plans may allow after-tax contributions up to the combined employee and employer limit of $72,000. If you're at least age 50 at the end of the calendar year, you can add a pre-tax or Roth catch-up contribution of $8,000 (or $11,250 if age 60–63, if your plan allows).

According to the SECURE 2.0 Act's higher earner rule, in 2026, catch-up contributions for earners whose FICA wages (typically Box 3 of Form W-2) exceed $150,000 in the previous tax year, must be designated as Roth after-tax contributions.

If your employer's plan does not offer a Roth contribution feature and you fall under the high-earner rule, you won't be able to make catch-up contributions to that plan.

If you have a workplace savings plan, you may be able to make after-tax contributions to bolster your savings.

Read Viewpoints: What to do with after-tax 401(k) contributions

Turning retirement savings into retirement income

Having an income plan in place before you retire can help you avoid surprises. For most people, Social Security and any pensions they have will provide an income base in retirement, with the rest coming from savings.

To start building your retirement income plan, consider these 4 steps:

  1. Identify your sources of predictable income. Start with any income you expect from Social Security, pensions, or annuities. These sources can help cover essential expenses such as housing, food, insurance, and health care.

    To help cover essential expenses that aren't met by Social Security or a pension, you may want to use some of your retirement savings to purchase an income annuity.4

    Read Viewpoints: How to feel financially secure in retirement

  2. Determine how much income your savings will need to provide. After estimating your predictable income, compare it with your expected spending. Any gap may need to be covered by withdrawals from your retirement savings. Fidelity estimates that many people may need savings to replace at least 45% of their preretirement income, after accounting for Social Security and pensions.5
  3. Figure out how much you can withdraw from savings annually. As a general guideline, consider withdrawing no more than 4% to 5% of your savings in the first year of retirement, then adjusting that amount annually for inflation.6
  4. Invest for growth potential and stay flexible. Even in retirement, a portion of your portfolio may need growth potential to help support future spending, keep pace with inflation, and meet legacy goals. Review your plan regularly and adjust as your expenses, health care needs, tax situation, and goals evolve over time.

    Read Viewpoints: 3 keys to your retirement income plan

  5. Get help making informed decisions about retirement by answering a few questions in this comprehensive guide covering Social Security, cash flow, investing, Medicare, and more: Retirement Decision Guide

3 hidden traps that can trip up your retirement plan

A strong retirement plan should cover income needs and consider future health care expenses, inflation, and taxes and required minimum distributions from retirement accounts.

On average, according to the 2026 Fidelity Retiree Health Care Cost Estimate, a 65-year-old individual may need $185,500 in after-tax savings to cover health care expenses in retirement.

Here are 3 often over-looked issues to consider.

  1. Managing health care costs: Retirement planning conversations should account for the impact long-term care costs have on individuals and their families.
  2. Look for ways to beat inflation: Social Security and certain pensions and annuities help keep up with inflation through annual cost-of-living adjustments or market-related performance. Additionally, choosing investments that have the potential to help keep pace with inflation, such as growth-oriented investments (e.g., stocks or stock mutual funds), Treasury Inflation-Protected Securities (TIPS), real estate securities,7 and commodities,8 may make sense to include as part of an age-appropriate, diversified portfolio.
  3. Be aware of required minimum distributions (RMDs): Certain retirement accounts require you to take minimum distributions starting at age 73. The RMD age will increase again to 75 in 2033. Accounts subject to RMDs include traditional IRAs; 401(k) and 403(b) plans; and SIMPLE and SEP IRAs. The annual deadline is December 31, but you may delay taking your first RMD up until April 1 of the year after you turn 73.9 It's important to know, however, that if you choose to wait until April 1 for your first RMD, it will mean taking 2 RMDs that year—one in April and one by the December 31 deadline. That additional income could have tax consequences for you. Read Viewpoints: 6 retirement tax moves most people miss.

The bottom line on planning for retirement

Successfully saving and investing for retirement is a lifelong journey. Sometimes the going will be easy and sometimes it may seem tougher. A clear sense of purpose can help you stick with it consistently through good times and bad.

Whether your retirement vision is detailed or still taking shape, consistently making it a financial priority can help bring it within reach.

Start a conversation

We'll meet you where you are on your financial journey and help you get to where you want to be.

More to explore

​The Retiree Health Care Cost Estimate (RHCCE) is based on a single person retiring in 2026, 65-years-old, with life expectancies that align with Society of Actuaries' RP-2014 Healthy Annuitant rates projected with Mortality Improvements Scale MP-2020 as of 2022. Actual assets needed may be more or less depending on actual health status, area of residence, and longevity. Estimate is net of taxes. The Fidelity Retiree Health Care Cost Estimate assumes individuals do not have employer-provided retiree health care coverage, but do qualify for the federal government’s insurance program, original Medicare. The calculation takes into account Medicare Part B base premiums and cost-sharing provisions (such as deductibles and coinsurance) associated with Medicare Part A and Part B (inpatient and outpatient medical insurance). It also considers Medicare Part D (prescription drug coverage) premiums and out-of-pocket costs, as well as certain services excluded by original Medicare. The estimate does not include other health-related expenses, such as over-the-counter medications, most dental services and long-term care.

Fidelity does not provide legal or tax advice. The information herein is general in nature and should not be considered legal or tax advice. Consult an attorney or tax professional regarding your specific situation.

Past performance is no guarantee of future results.

This information is intended to be educational and is not tailored to the investment needs of any specific investor.

1. Fidelity has developed a series of salary multipliers in order to provide participants with one measure of how their current retirement savings might be compared to potential income needs in retirement. The salary multiplier suggested is based solely on your current age. In developing the series of salary multipliers corresponding to age, Fidelity assumed age-based asset allocations consistent with the equity glide path of a typical target date retirement fund, a 15% savings rate, a 1.5% constant real wage growth, a retirement age of 67 and a planning age through 93. The replacement annual income target is defined as 45% of pre-retirement annual income and assumes no pension income. This target is based on Consumer Expenditure Survey (BLS), retirement Statistics of Income Tax Stat, IRS tax brackets and Social Security Benefit Calculators. Fidelity developed the salary multipliers through multiple market simulations based on historical market data, assuming poor market conditions to support a 90% confidence level of success.

These simulations take into account the volatility that a typical target date asset allocation might experience under different market conditions. Volatility of the stocks, bonds and short-term asset classes is based on the historical annual data from 1926 through the most recent year-end data available from Ibbotson Associates, Inc. Stocks (domestic and foreign) are represented by Ibbotson Associates SBBI S&P 500 Total Return Index, bonds are represented by Ibbotson Associates SBBI US Intermediate Term Government Bonds Total Return Index, and short term are represented by Ibbotson Associates SBBI 30-day US Treasury Bills Total Return Index, respectively. It is not possible to invest directly in an index. All indices include reinvestment of dividends and interest income. All calculations are purely hypothetical and a suggested salary multiplier is not a guarantee of future results; it does not reflect the return of any particular investment or take into consideration the composition of a participant’s particular account. The salary multiplier is intended only to be one source of information that may help you assess your retirement income needs. Remember, past performance is no guarantee of future results. Performance returns for actual investments will generally be reduced by fees or expenses not reflected in these hypothetical calculations. Returns also will generally be reduced by taxes.

2. With respect to federal taxation only. Contributions, investment earnings, and distributions may or may not be subject to state taxation. Please consult with your tax professional regarding your specific situation. 3. Fidelity's suggested total pre-tax savings goal of 15% of annual income (including employer contributions) is based on our research, which indicates that most people would need to contribute this amount from an assumed starting age of 25 through an assumed retirement age of 67 to potentially support a replacement annual income rate equal to 45% of preretirement annual income (assuming no pension income) through age 93. The income replacement target is based on Consumer Expenditure Survey (BLS), Statistics of Income Tax Stats, IRS tax brackets, and Social Security Benefit Calculators. The 45% income replacement target (excluding Social Security and assuming no pension income) from retirement savings was found to be fairly consistent across a salary range of $50,000-$300,000; therefore the savings rate suggestions may have limited applicability if your income is outside that range. Individuals may need to save more or less than 15% depending on retirement age, desired retirement lifestyle, assets saved to date, and other factors. See footnote 1 for investment growth assumptions. 4. Guaranteed lifetime income is subject to the claims-paying ability of the issuing insurance company. 5. The income replacement rate is the percentage of preretirement income that an individual should target replacing in retirement. The income replacement targets are based on Consumer Expenditure Survey (BLS), Statistics of Income Tax Stat, IRS tax brackets, and Social Security Benefit Calculators. The 45% income replacement target assumes no pension income, and a retirement and Social Security claiming age of 67, which is the full Social Security benefit age for those born in 1960 or later. For an earlier retirement and claiming age, this target goes up due to lower Social Security retirement benefits. Similarly, the target goes down for a later retirement age. For a retirement age of 65, this target is defined as 50% of preretirement annual income and for a retirement age of 70, this target is defined as 40% of preretirement income. 6. The sustainable withdrawal rate is defined as an inflation-adjusted annual withdrawal rate, and expressed as a percentage of your initial (at retirement) savings balance. This rate is estimated to be 4.5%, assuming a retirement age of 67 and a planning age through 93. See footnote No. 1 for investment growth assumptions. 7.

A common stock REIT is a security that sells like a stock on the major exchanges and invests in real estate directly, either through properties or mortgages. A REIT is required to invest at least 75% of total assets in real estate and to distribute 90% of its taxable income to investors.

Stock markets are volatile and can fluctuate significantly in response to company, industry, political, regulatory, market, or economic developments. Investing in stock involves risks, including the loss of principal.

Illiquidity is an inherent risk associated with investing in real estate and REITs. There is no guarantee that the issuer of a REIT will maintain the secondary market for its shares, and redemptions may be at a price that is more or less than the original price paid. Changes in real estate values or economic downturns can have a significant negative effect on issuers in the real estate industry.

8.

The commodities industry can be significantly affected by commodity prices, world events, import controls, worldwide competition, government regulations, and economic conditions.

9. Required minimum distribution rules do not apply to participants in 401(k) plans who are less than 5% owners of employers that sponsor a workplace plan, until they retire or turn 73, whichever is later.

Fidelity Freedom Funds are designed for investors who anticipate retiring in or within a few years of the fund's target retirement year at or around age 65 and plan to gradually withdraw the value of their account in the fund over time. Except for the Freedom Retirement Fund, the funds' asset allocation strategy becomes increasingly conservative as the funds approach the target date and beyond. Ultimately, the funds are expected to merge with the Freedom Retirement Fund. The investment risk of each Fidelity Freedom Fund changes over time as its asset allocation changes. These risks are subject to the asset allocation decisions of the Investment Adviser. Pursuant to the Adviser's ability to use an active asset allocation strategy, investors may be subject to a different risk profile compared to the fund's neutral asset allocation strategy shown in its glide path. The funds are subject to the volatility of the financial markets, including that of equity and fixed income investments in the U.S. and abroad, and may be subject to risks associated with investing in high-yield, small-cap, commodity-linked and foreign securities. Leverage can increase market exposure, magnify investment risks, and cause losses to be realized more quickly. No target date fund is considered a complete retirement program and there is no guarantee any single fund will provide sufficient retirement income at or through retirement. Principal invested is not guaranteed at any time, including at or after the funds' target dates.

Keep in mind that investing involves risk. The value of your investment will fluctuate over time, and you may gain or lose money.

Views expressed are as of the date indicated, based on the information available at that time, and may change based on market or other conditions. Unless otherwise noted, the opinions provided are those of the speaker or author and not necessarily those of Fidelity Investments or its affiliates. Fidelity does not assume any duty to update any of the information.

Investing involves risk, including risk of loss.

In general, the bond market is volatile, and fixed income securities carry interest rate risk. (As interest rates rise, bond prices usually fall, and vice versa. This effect is usually more pronounced for longer-term securities). Fixed income securities also carry inflation risk, liquidity risk, call risk and credit and default risks for both issuers and counterparties. Lower-quality fixed income securities involve greater risk of default or price changes due to potential changes in the credit quality of the issuer. Foreign investments involve greater risks than U.S. investments, and can decline significantly in response to adverse issuer, political, regulatory, market, and economic risks. Any fixed-income security sold or redeemed prior to maturity may be subject to loss.

Stock markets are volatile and can fluctuate significantly in response to company, industry, political, regulatory, market, or economic developments. Investing in stock involves risks, including the loss of principal.

Diversification and asset allocation do not ensure a profit or guarantee against loss.

The information provided herein is general in nature. It is not intended, nor should it be construed, as legal or tax advice. Because the administration of an HSA is a taxpayer responsibility, you are strongly encouraged to consult your tax advisor before opening an HSA. You are also encouraged to review information available from the Internal Revenue Service (IRS) for taxpayers, which can be found on the IRS website at IRS.gov. You can find IRS Publication 969, Health Savings Accounts and Other Tax-Favored Health Plans, and IRS Publication 502, Medical and Dental Expenses, online, or you can call the IRS to request a copy of each at 800-829-3676.

Before investing, consider the funds' investment objectives, risks, charges, and expenses. Contact Fidelity for a prospectus or, if available, a summary prospectus containing this information. Read it carefully.

Fidelity Brokerage Services LLC, Member NYSE, SIPC, 900 Salem Street, Smithfield, RI 02917

1078579.5.0