


Imagine you’re about to wrap up your career after decades of hard work, and you’re looking forward to the freedom of retirement, including choosing where you’d like to live.
That might mean moving closer to your children, who may live in different states, or maybe you’re considering trading cold Northeast winters for retirement in the warmer climate of the Sun Belt. But as you research your options, you quickly realize that tax rates on retirement withdrawals can vary widely by state—and that where you decide to live could have a dramatic impact on your retirement nest egg.
Suddenly, choosing where you'll spend your retirement years becomes as much a strategic financial decision as it is about lifestyle. The difference between retiring in a lower-tax state versus a higher-tax one could potentially result in thousands of dollars of savings each year.
While income from Social Security is generally exempt from state taxes in all but 9 states as of tax-year 2025, withdrawals from workplace retirement accounts, traditional IRAs, and pensions are subject to income taxes in most states, in addition to federal taxes. Other state taxes to consider in retirement include property, sales, estate, and inheritance taxes. If you’re thinking about relocating in retirement, understanding how these taxes affect your bottom line could help your withdrawals go further—and your retirement last longer.
To help you decide where you might live in retirement, we’ve crunched the numbers on each state if you’re making traditional IRA withdrawals of $100,000 annually in retirement. We examined the effective state taxes imposed on withdrawals from traditional IRAs, factoring in exemptions, deductions, and credits on those withdrawals. We do not consider state standard deductions and exemptions; instead, we use the federal standard deductions. All state tax information is for tax year 2025.
Except where indicated, the following analysis of best and worst states for taxes is based on an assumption of IRA withdrawals of $100,000 annually. Note: While Washington, DC, is not a state, it is included in our analysis.
What are the best states to retire for taxes on retirement withdrawals?
At the top of the list are the 13 states where retirees pay no state taxes on IRA withdrawals. Just 9 states have no income tax. These are Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. An additional 4 states do not tax income from IRAs. These are Iowa, Illinois, Mississippi, and Pennsylvania.
Imagine a married couple with $100,000 in withdrawals from IRAs in high-tax Oregon and paying a 5.39% effective state income tax rate. That same couple would pay a 0% effective tax rate if they moved to Iowa.
Iowa does not tax withdrawals from IRAs, 401(k)s, 403(b)s, and similar retirement accounts for people who are 55 years of age or older by the end of the year (or qualify due to disability or as a qualifying surviving spouse). Although the couple would still owe federal income tax on the $100,000, the reduction in total taxes paid due to the state treatment of IRA withdrawals could really add up. Invested for 10 years at a hypothetical 7% annual rate of return, the $5,390 saved at the end of each year could leave them with more than $74,000 in additional savings.1
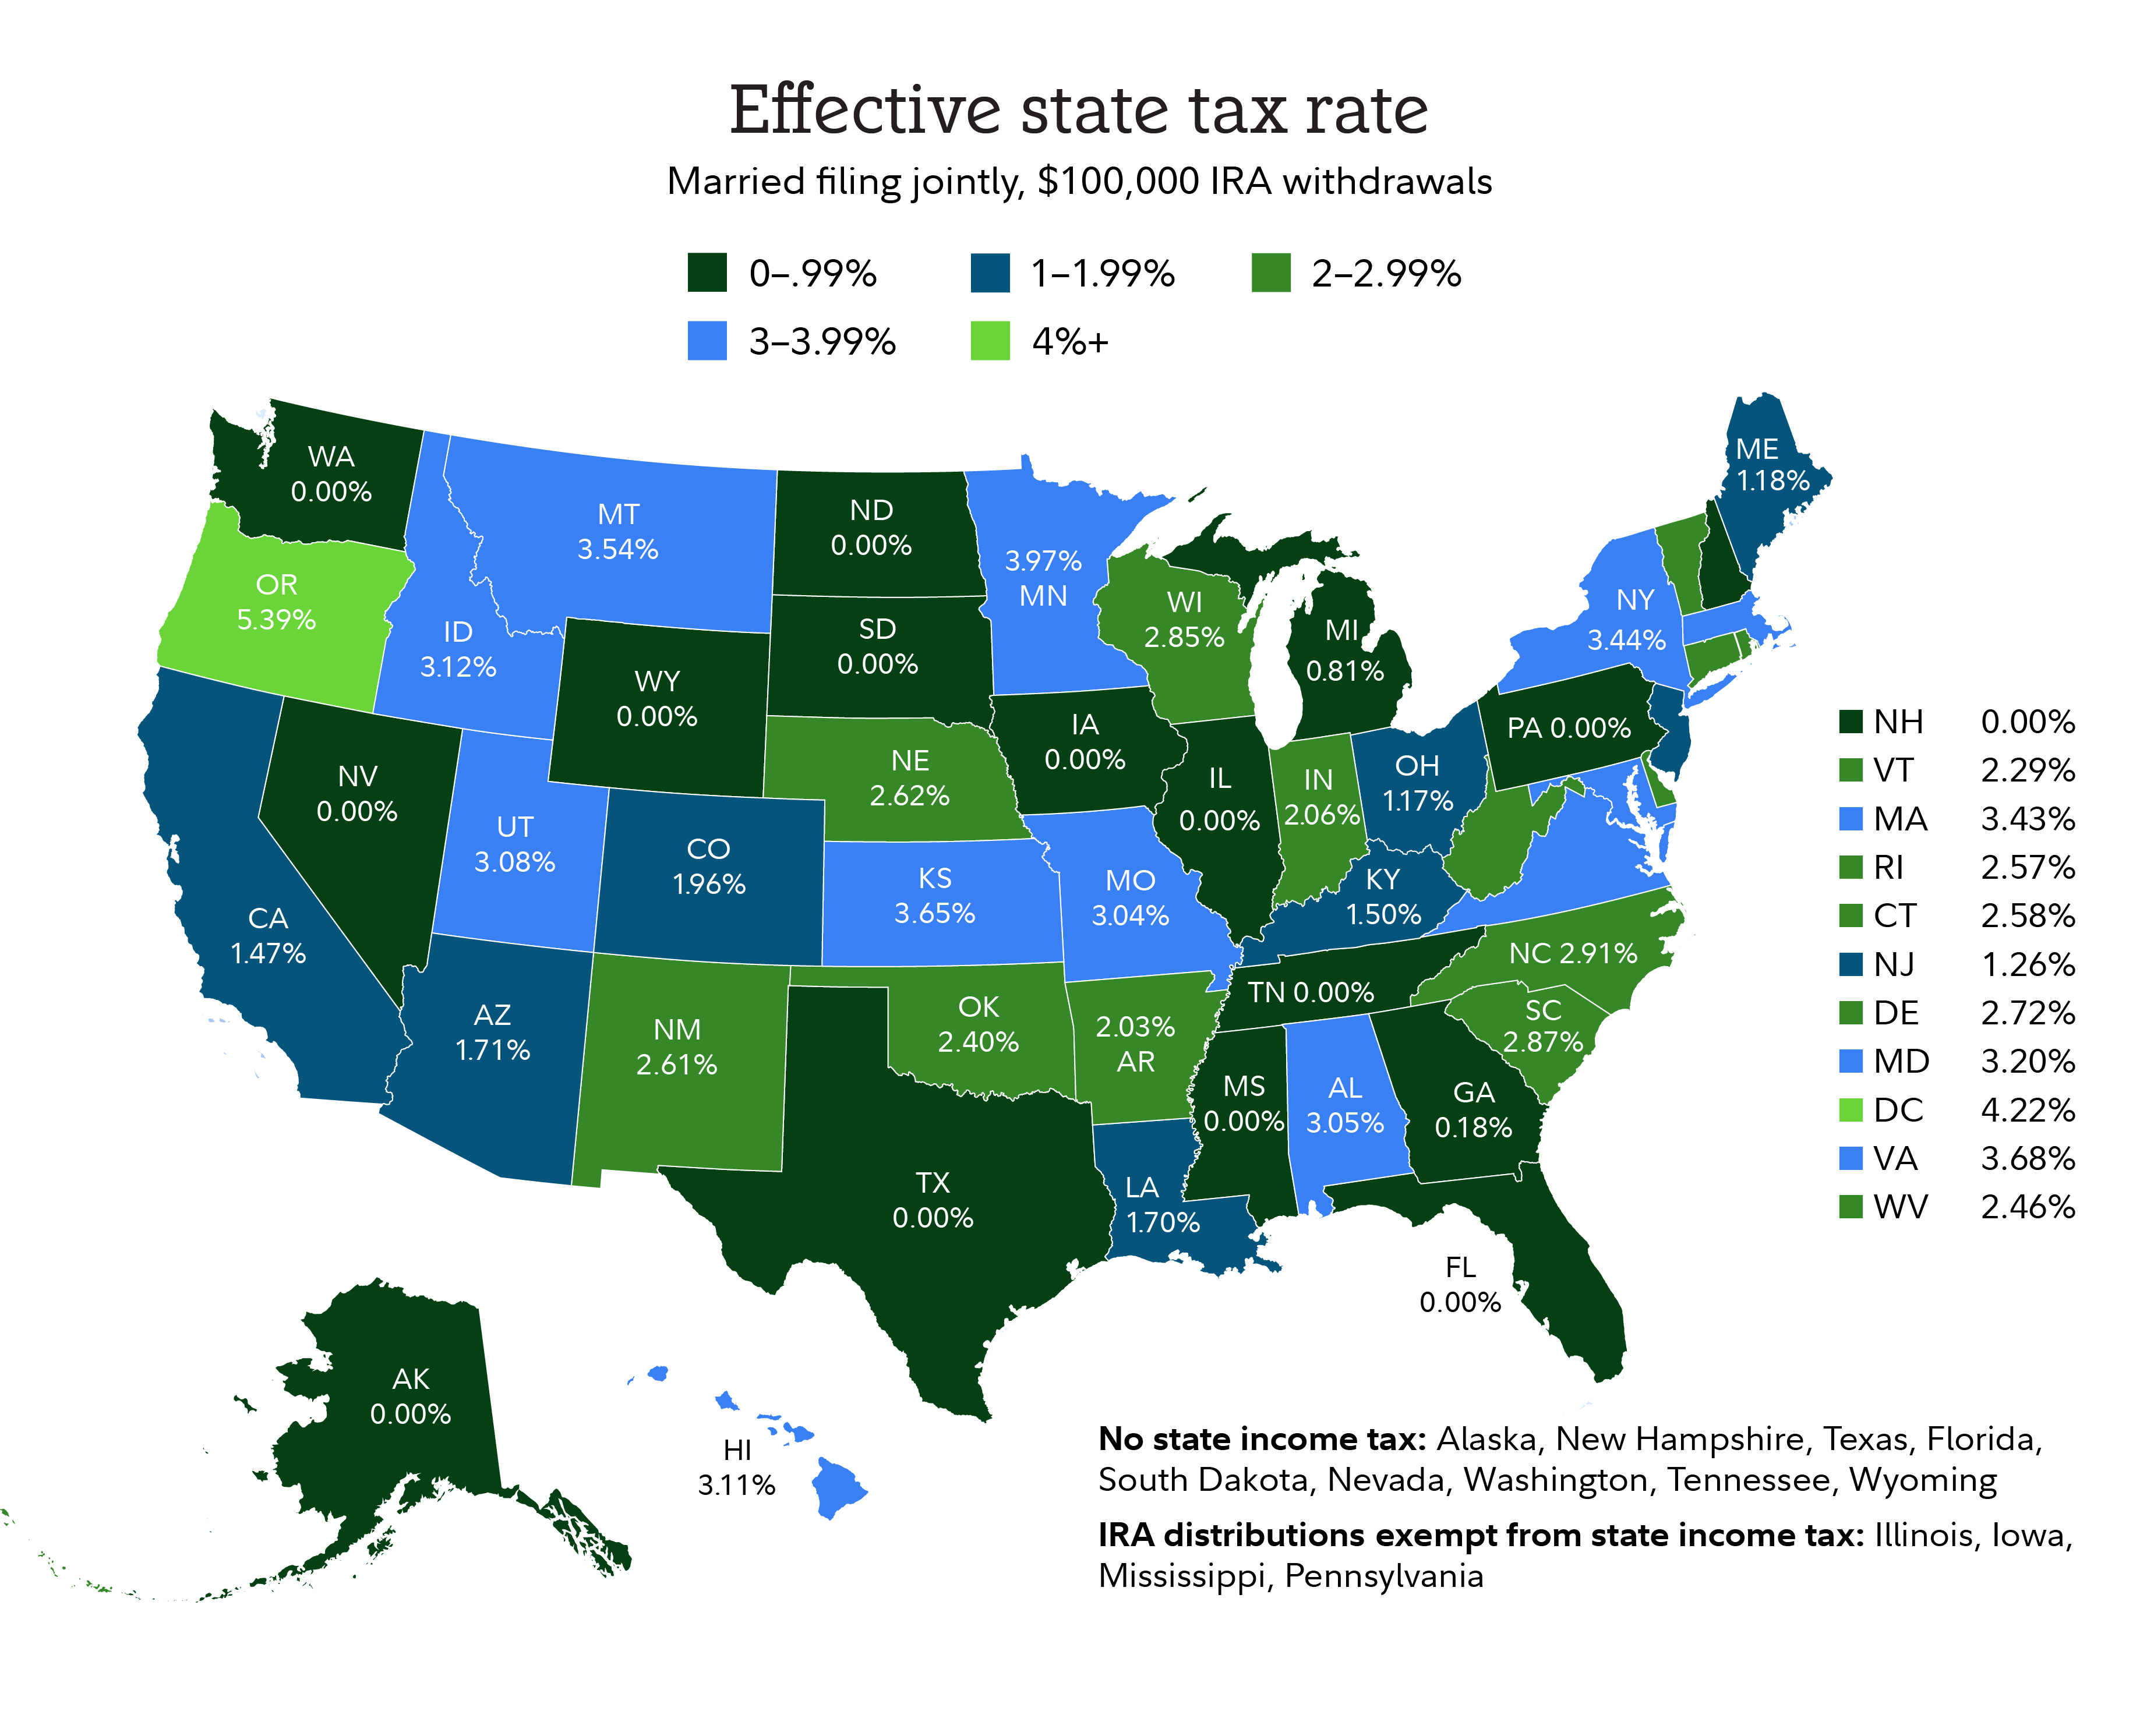
Chart assumes income is IRA withdrawals of $100,000 rather than earned income. State income tax brackets are applied. Federal standard deductions based on filing status ($31,500 for married filing jointly or $15,750 for single) are used in place of state standard deductions and exemptions. Age-based exemptions are not used. No tax credits are assumed. All data is as of 2025. Tax law may have changed since that date.
AGI-based phaseouts on IRA exemptions are not considered. States with AGI-based phaseouts do not have an exemption applied to IRA withdrawals when calculating effective state tax rates.
North Dakota generally taxes IRA withdrawals, but it provides a broad income exemption for many couples who are married filing jointly that can reduce or eliminate the tax.
For Connecticut, the analysis does not account for the phaseout of the lowest bracket or either of the benefit recaptures when calculating the tax liability. For Arkansas, the analysis blends the lower-earning tax rate schedule with the higher-earning schedule for the purposes of calculating tax liability. Where a maximum exemption amount differs by filing status, the maximum for a single filer is used.
States with the highest and lowest effective tax rates for retirees
In the 2 graphics below, we illustrate the range of these effective income tax rates for both single people and married couples with $100,000 in taxable IRA income. You may be surprised about some of the best and worst states for taxes on retirement income, particularly when it comes to marital status.
Among the 37 states and Washington, DC, that do tax IRA withdrawals, the effective state tax rate ranges from a high of 6.90% for Oregon to a low of 0.66% for North Dakota for single filers with $100,000 of IRA distributions. For married filers with the same amount of withdrawals, the rate ranges from a high of 5.39% for Oregon to a low of 0.18% for Georgia. Good to know: North Dakota generally taxes IRA withdrawals, but it provides a broad income exemption for many couples that can reduce or eliminate the tax. Georgia offers the next-lowest rate for married filers after North Dakota's effective rate of 0%.
.png "List chart showing best states to retire for taxes, featuring the 10 highest effective tax rates by state on $100,000 in IRA withdrawals for married couples filing jointly and single filers, across all U.S. states")
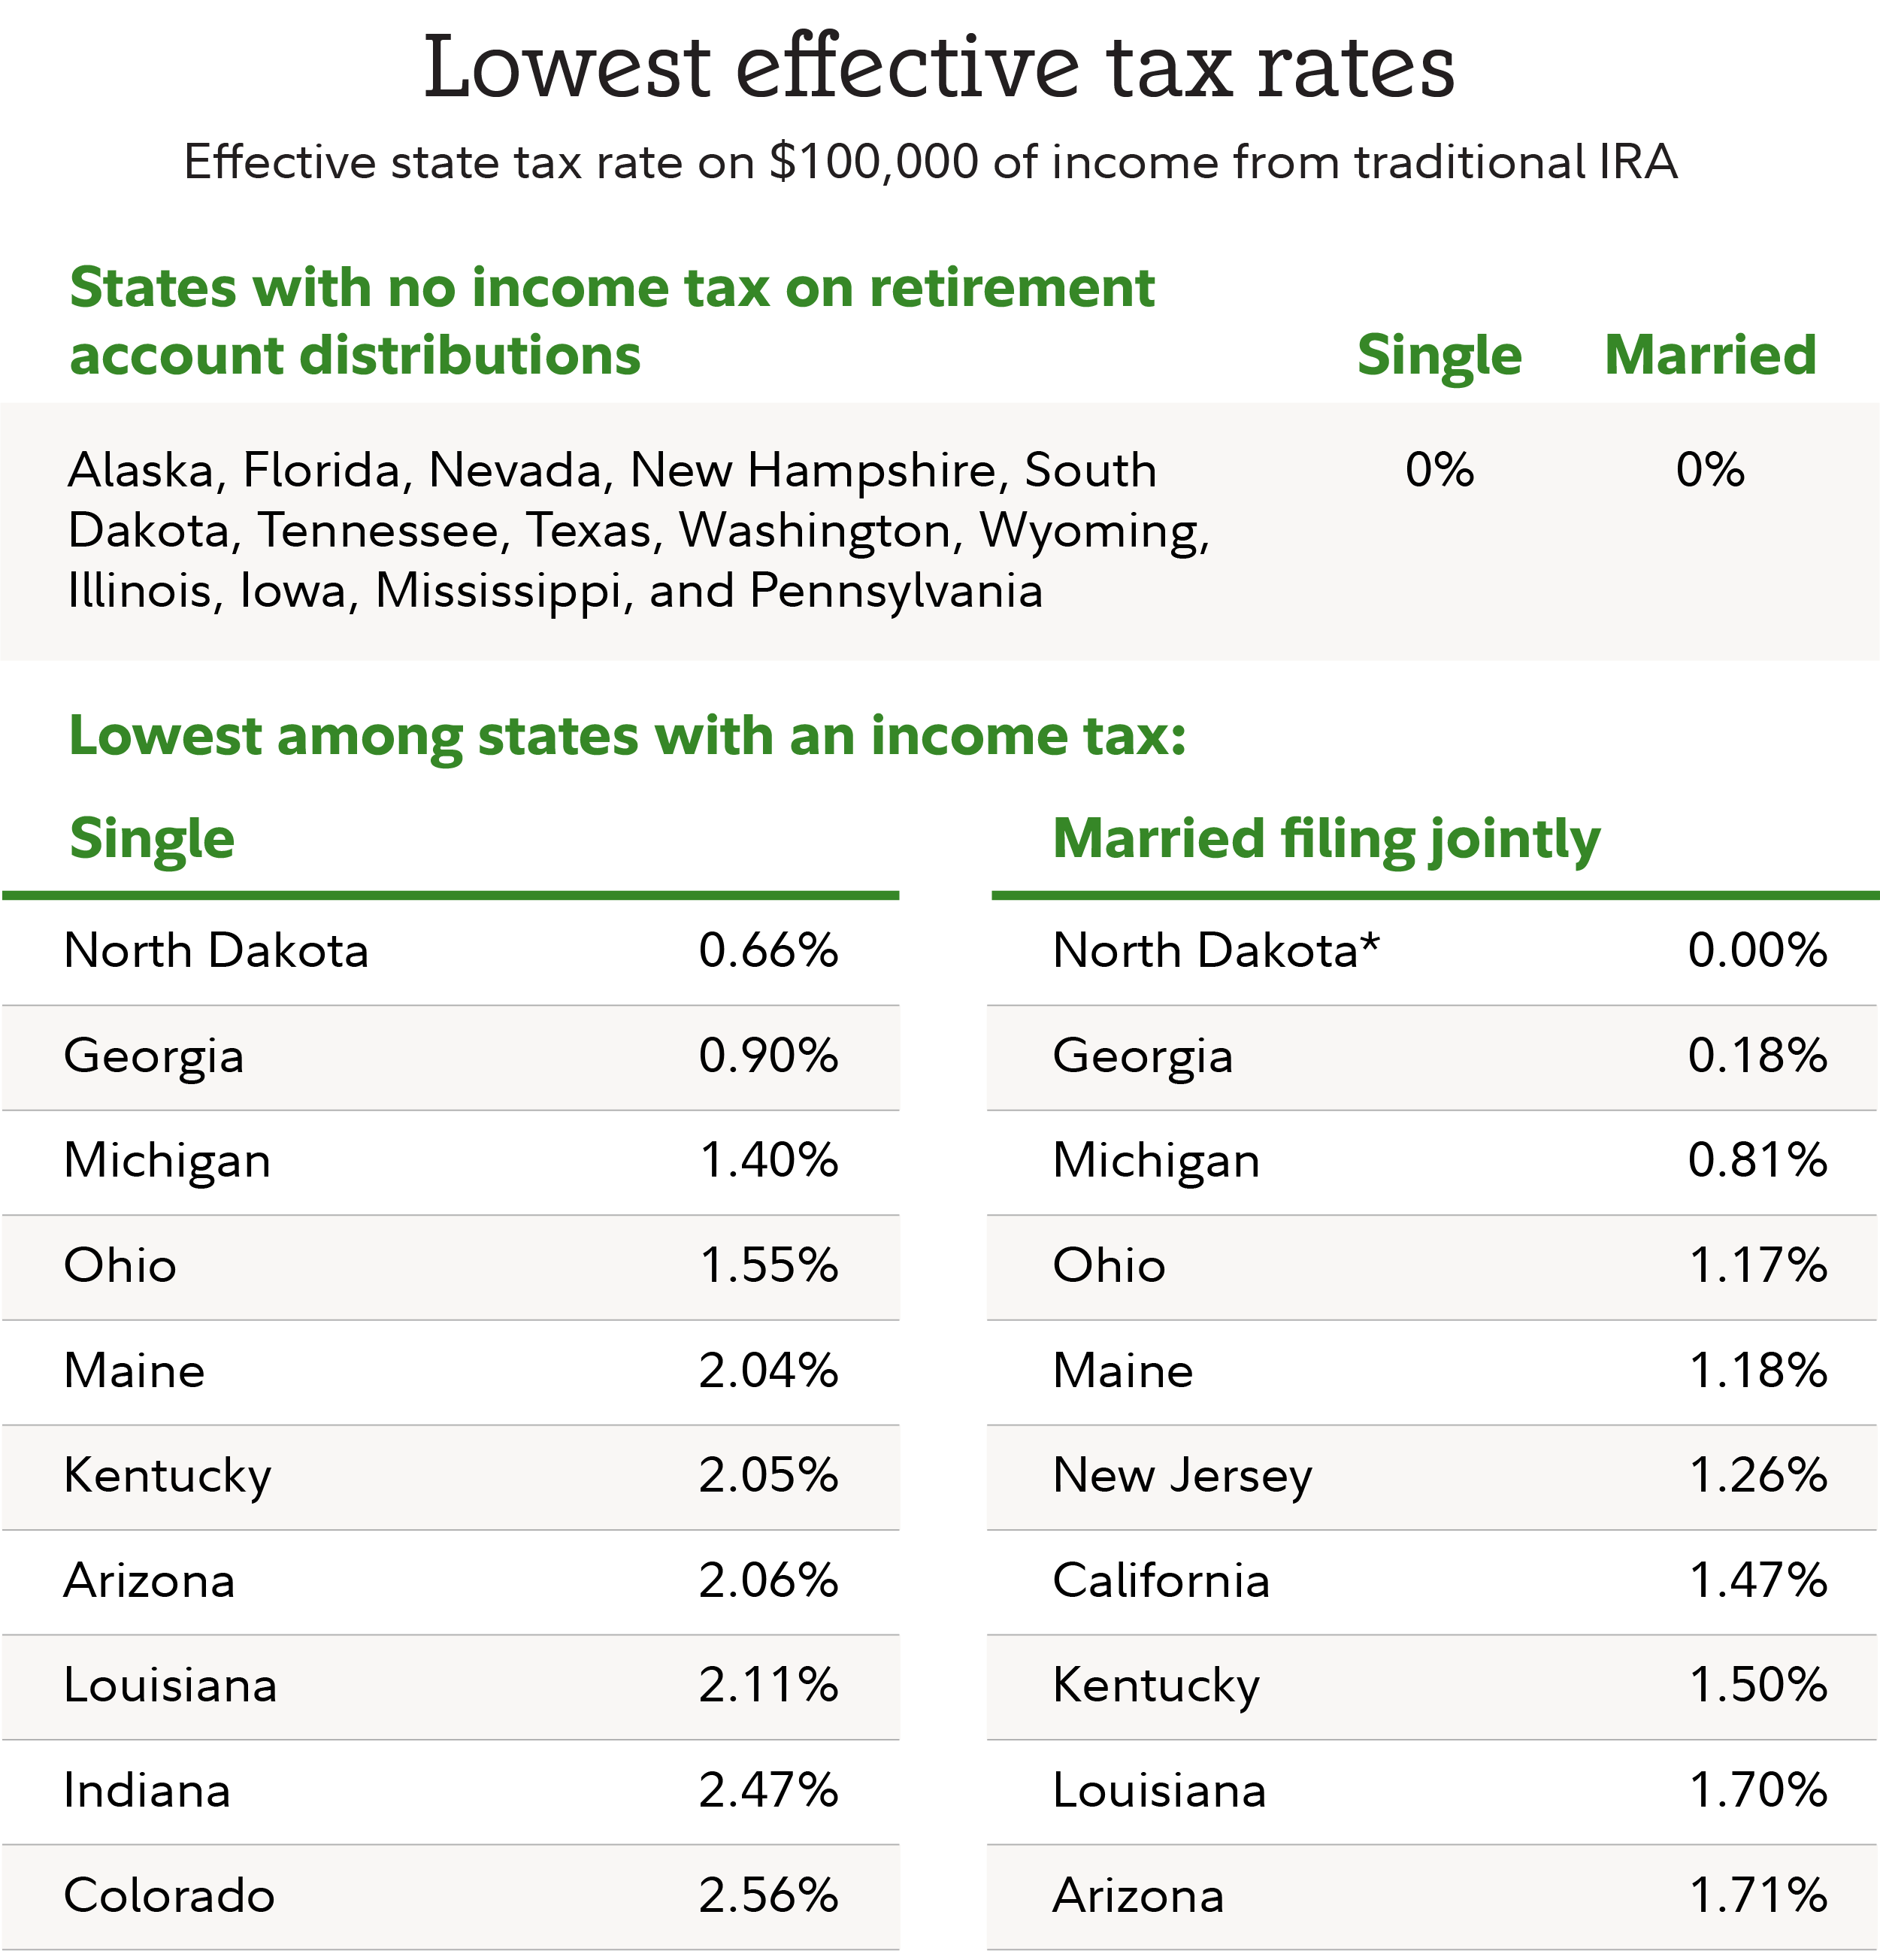
Chart assumes income is IRA withdrawals of $100,000 rather than earned income. State income tax brackets are applied. Federal standard deductions based on filing status ($31,500 for married filing jointly or $15,750 for single) are used in place of state standard deductions and exemptions. Age-based exemptions are not used. No tax credits are assumed. All data is as of 2025. Tax law may have changed since that date.
AGI-based phaseouts on IRA exemptions are not considered. States with AGI-based phaseouts do not have an exemption applied to IRA withdrawals when calculating effective state tax rates.
*North Dakota generally taxes IRA withdrawals, but it provides a broad income exemption for many couples who are married filing jointly that can reduce or eliminate the tax.
For Connecticut, the analysis does not account for the phaseout of the lowest bracket or either of the benefit recaptures when calculating the tax liability. For Arkansas, the analysis blends the lower-earning tax rate schedule with the higher-earning schedule for the purposes of calculating tax liability. Where a maximum exemption amount differs by filing status, the maximum for a single filer is used.
Surprising takeaways for retirees
- Oregon is the most expensive state for both single people and those who are married couples filing jointly, followed by Washington, DC.
- New Jersey, otherwise a high-cost, high-tax Northeastern state with high sales and property taxes, is one of the most favorable states of those that tax IRA withdrawals, for married joint filers making withdrawals from IRAs. A married couple filing jointly and taking $100,000 in withdrawals from an IRA would pay a state effective tax rate of 1.26%. Also worth noting: While New Jersey ranks among the lower-tax states for single filers, where residents would pay a 3.11% rate on $100,000 of IRA income, that’s more than twice the rate of married joint filers.
- Quite a few states known for high income taxes in general are somewhat more favorable for retirees who are taking $100,000 in retirement account withdrawals, particularly those who are married. California, for example, with a tax rate of 1.47% for joint filers ranks sixth nationally for such filers, although it ranks among the higher-tax states for single filers, as well as the 5 highest-tax states for higher-income filers.
- Similarly, some Sun Belt states may have relatively higher effective tax rates on $100,000 of withdrawals from an IRA than their reputations for retirement affordability might suggest. For example, New Mexico, with an effective tax rate of 2.61% for married filers and 3.49% for single filers, ranks near the bottom third of states.
- Contrary to preconceived notions about affordability in general, some Midwestern states also have surprisingly high tax rates for people taking $100,000 of withdrawals from an IRA. Kansas, with an effective tax rate of 3.65% for married filers and 4.5% for single filers, has higher tax rates than Massachusetts, Connecticut, and Maryland for both single and married filers living on retirement income.
People with higher taxable withdrawals from IRAs may find some surprises as well. In the table below, we show the effective state income tax rates for both single people and married couples filing jointly with $250,000 in taxable IRA income. The table focuses on the states that tax these withdrawals the most.
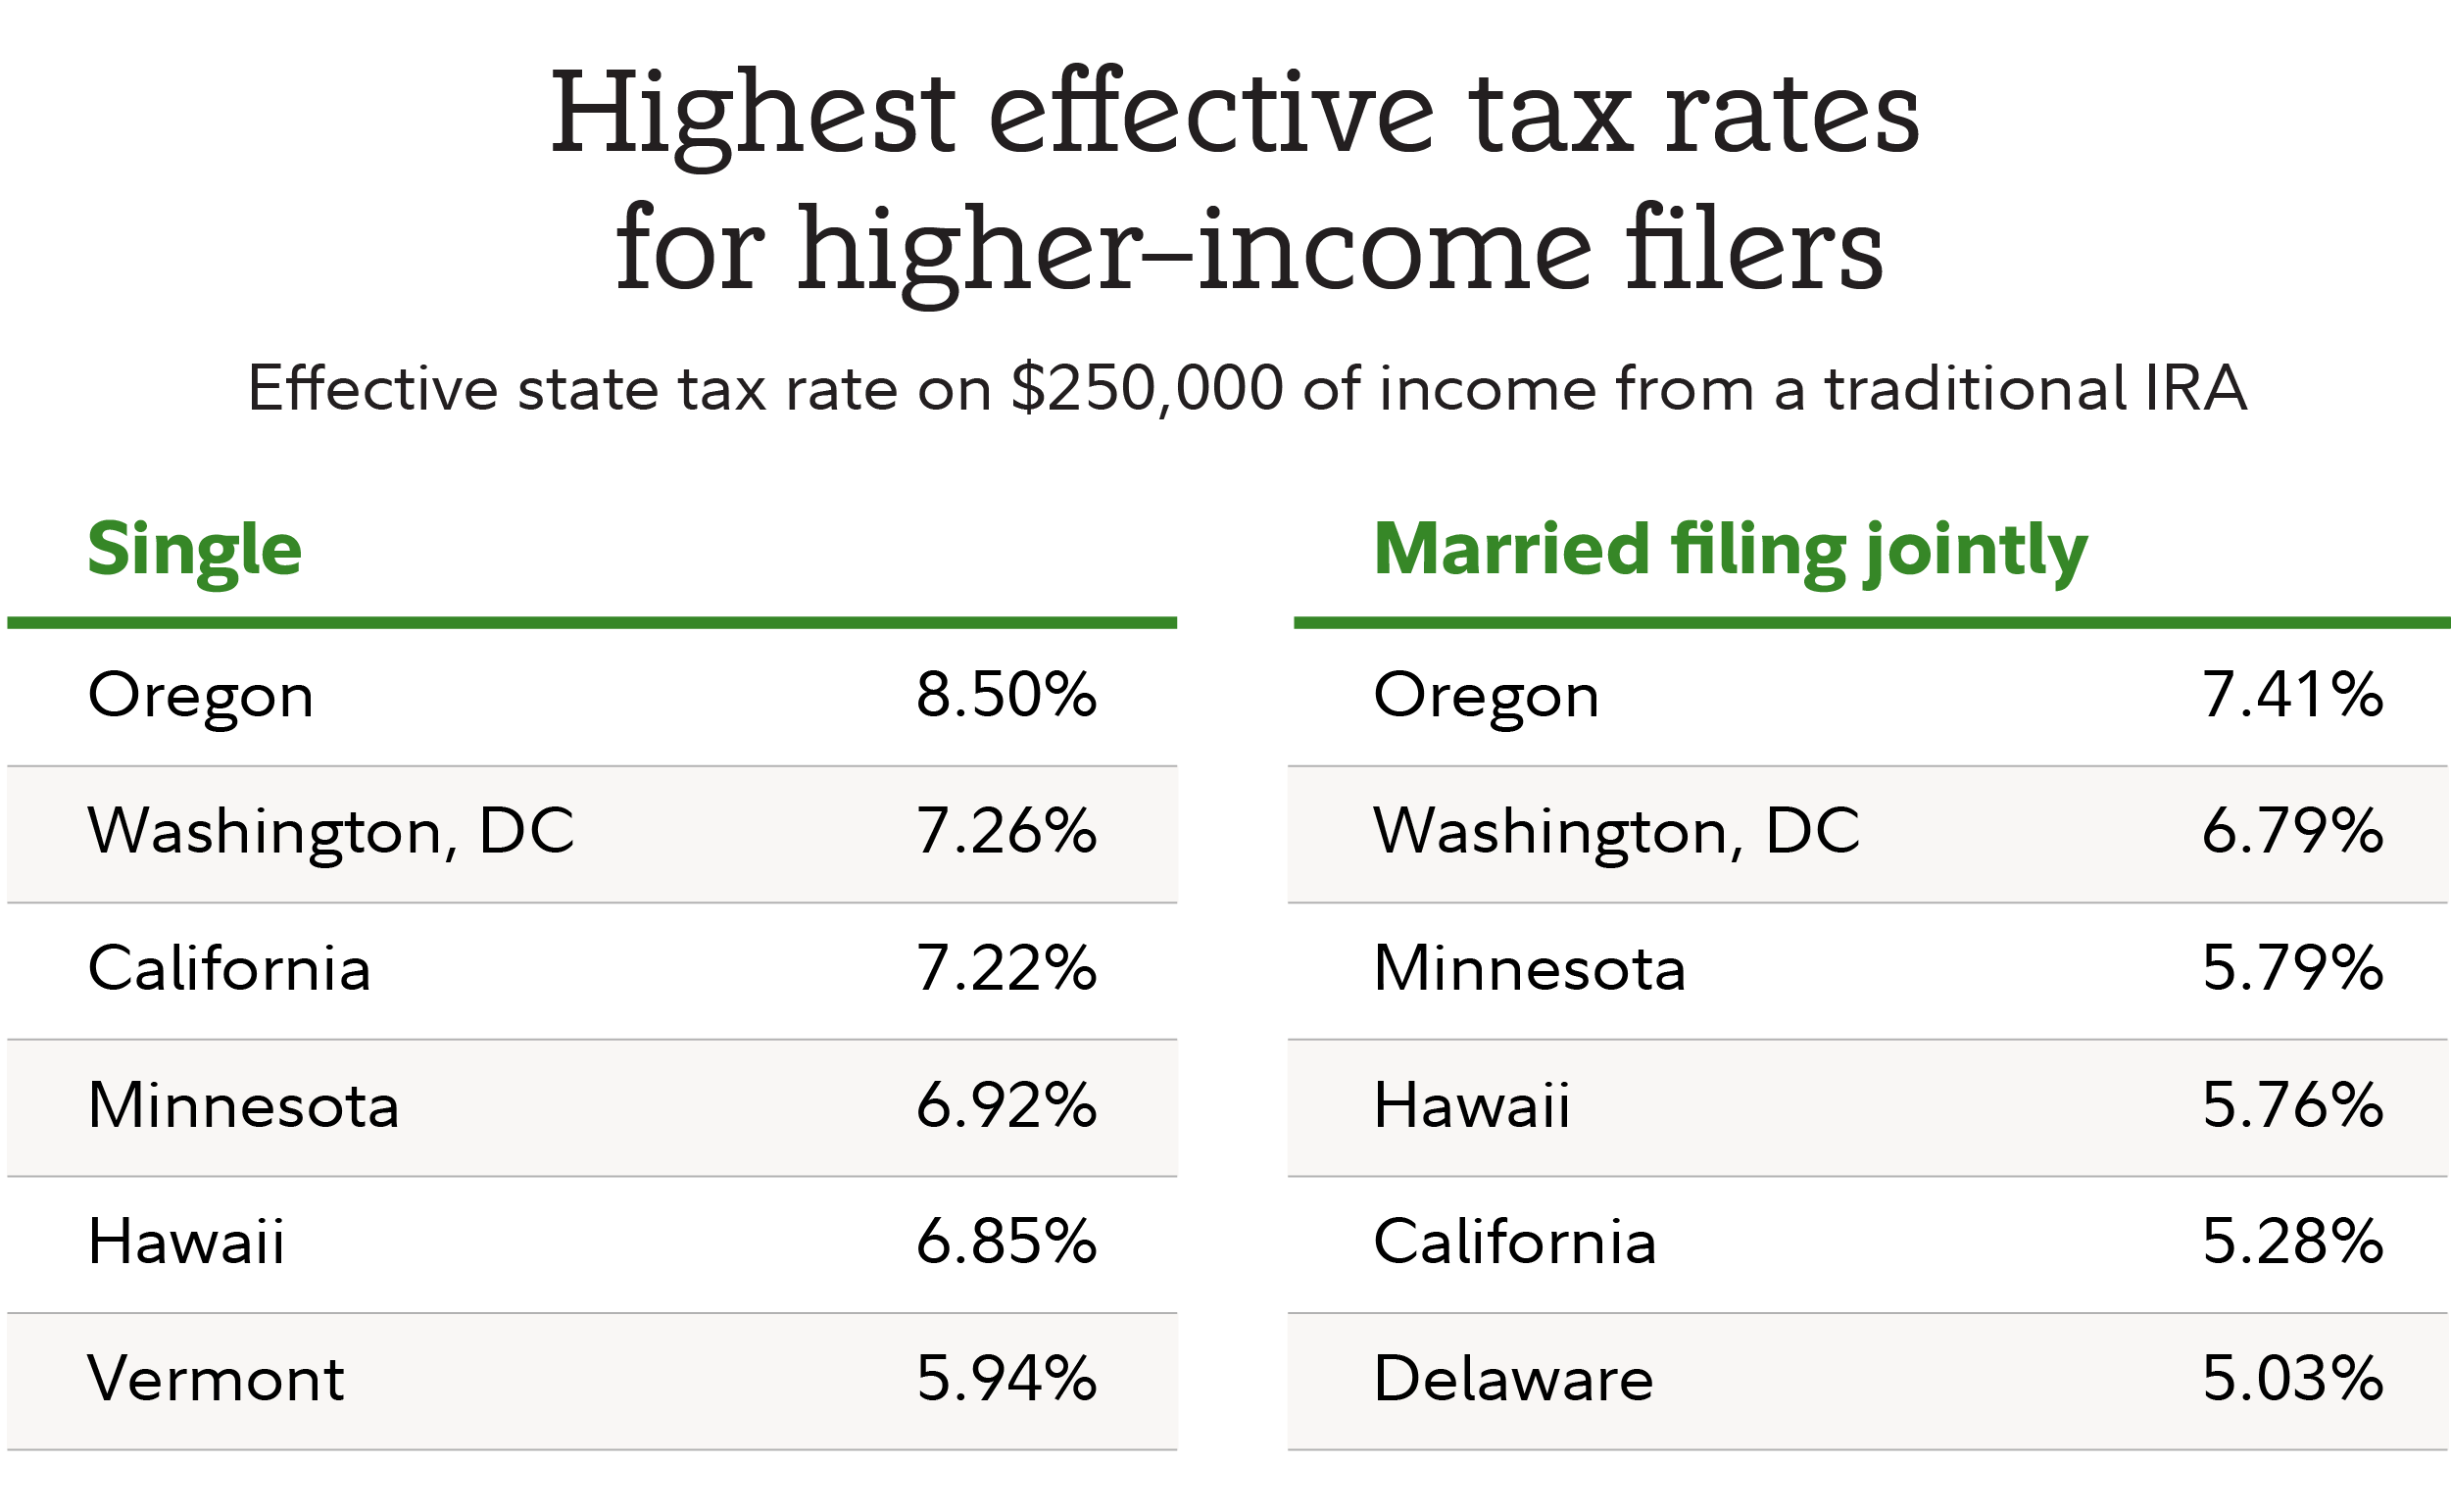
Chart assumes income is IRA withdrawals of $250,000 rather than earned income. State income tax brackets are applied. Federal standard deductions based on filing status ($31,500 for married filing jointly or $15,750 for single) are used in place of state standard deductions and exemptions. Age-based exemptions are not used. No tax credits are assumed. All data is as of 2025. Tax law may have changed since that date.
AGI-based phaseouts on IRA exemptions are not considered. States with AGI-based phaseouts do not have an exemption applied to IRA withdrawals when calculating effective state tax rates.
For Connecticut, the analysis does not account for the phaseout of the lowest bracket or either of the benefit recaptures when calculating the tax liability. For Arkansas, the analysis blends the lower-earning tax rate schedule with the higher-earning schedule for the purposes of calculating tax liability. Where a maximum exemption amount differs by filing status, the maximum for a single filer is used.
Oregon remains the highest-tax state for single filers and married joint filers with IRA withdrawals of $250,000. And Washington, DC, again ranks as the second most-expensive area.
Whereas California is more favorable from a tax perspective for married joint filers with $100,000 of withdrawals, it’s among the highest-tax states for both single and married joint filers with withdrawals of $250,000. Similarly, Vermont, also one of the Northeast’s generally higher tax states—although not in the top 10 highest-tax states for more modest withdrawals—has the sixth-highest effective state tax rate for single filers with $250,000 of IRA withdrawals.
Finally, Delaware, which runs roughly in the middle of state rates for both types of filers for more modest incomes, has among the highest effective state tax rates for married filers with $250,000 of IRA withdrawals.
Differences by marital status
Across all states where IRA withdrawals are taxed, married people filing jointly generally have an advantage over single filers. The effective state tax rates for couples taking $100,000 in IRA withdrawals are about 1 percentage point less on average than their unmarried counterparts, with the gap exceeding 2 percentage points in states such as California and Hawaii. That could be a particularly important consideration if you are recently separated or widowed, in which case you could experience a sharp increase in your effective tax rate.
Note: Federal tax law allows a recently widowed person to file as qualifying surviving spouse in the 2 years following their spouse’s death, essentially preserving their joint filing tax status during this time period. Claiming qualifying surviving spouse status during this period requires having a dependent child, as well as meeting certain additional eligibility criteria.
Understand the impact of state taxes on IRA withdrawals
So while income tax is only one reason a person may move from one state to another, by understanding how much of your retirement income may be taxed by the state in which you live, you can make sure the nest egg you’ve spent a lifetime growing can last longer. Remember, it’s always best to consult with a tax professional for guidance about your specific financial situation.