

Your credit health
Your credit score is one of the factors that helps lenders determine how much you can borrow. Usually the higher your credit score, the lower your interest rate, which can save thousands of dollars in the long run.
To add, you're entitled by federal law to a free annual credit report from each of the major credit reporting agencies: Equifax®, Experian®, and TransUnion®. Although you won't have to submit copies of your credit report, to find out if your current credit qualifies you for a good mortgage, you should check your credit reports and verify that all your information is correct and up to date. Having your credit checked is part of the process of applying for a mortgage. Your credit score and the information on your credit report help determine likelihood you'll be able to get a mortgage and at what interest rate.
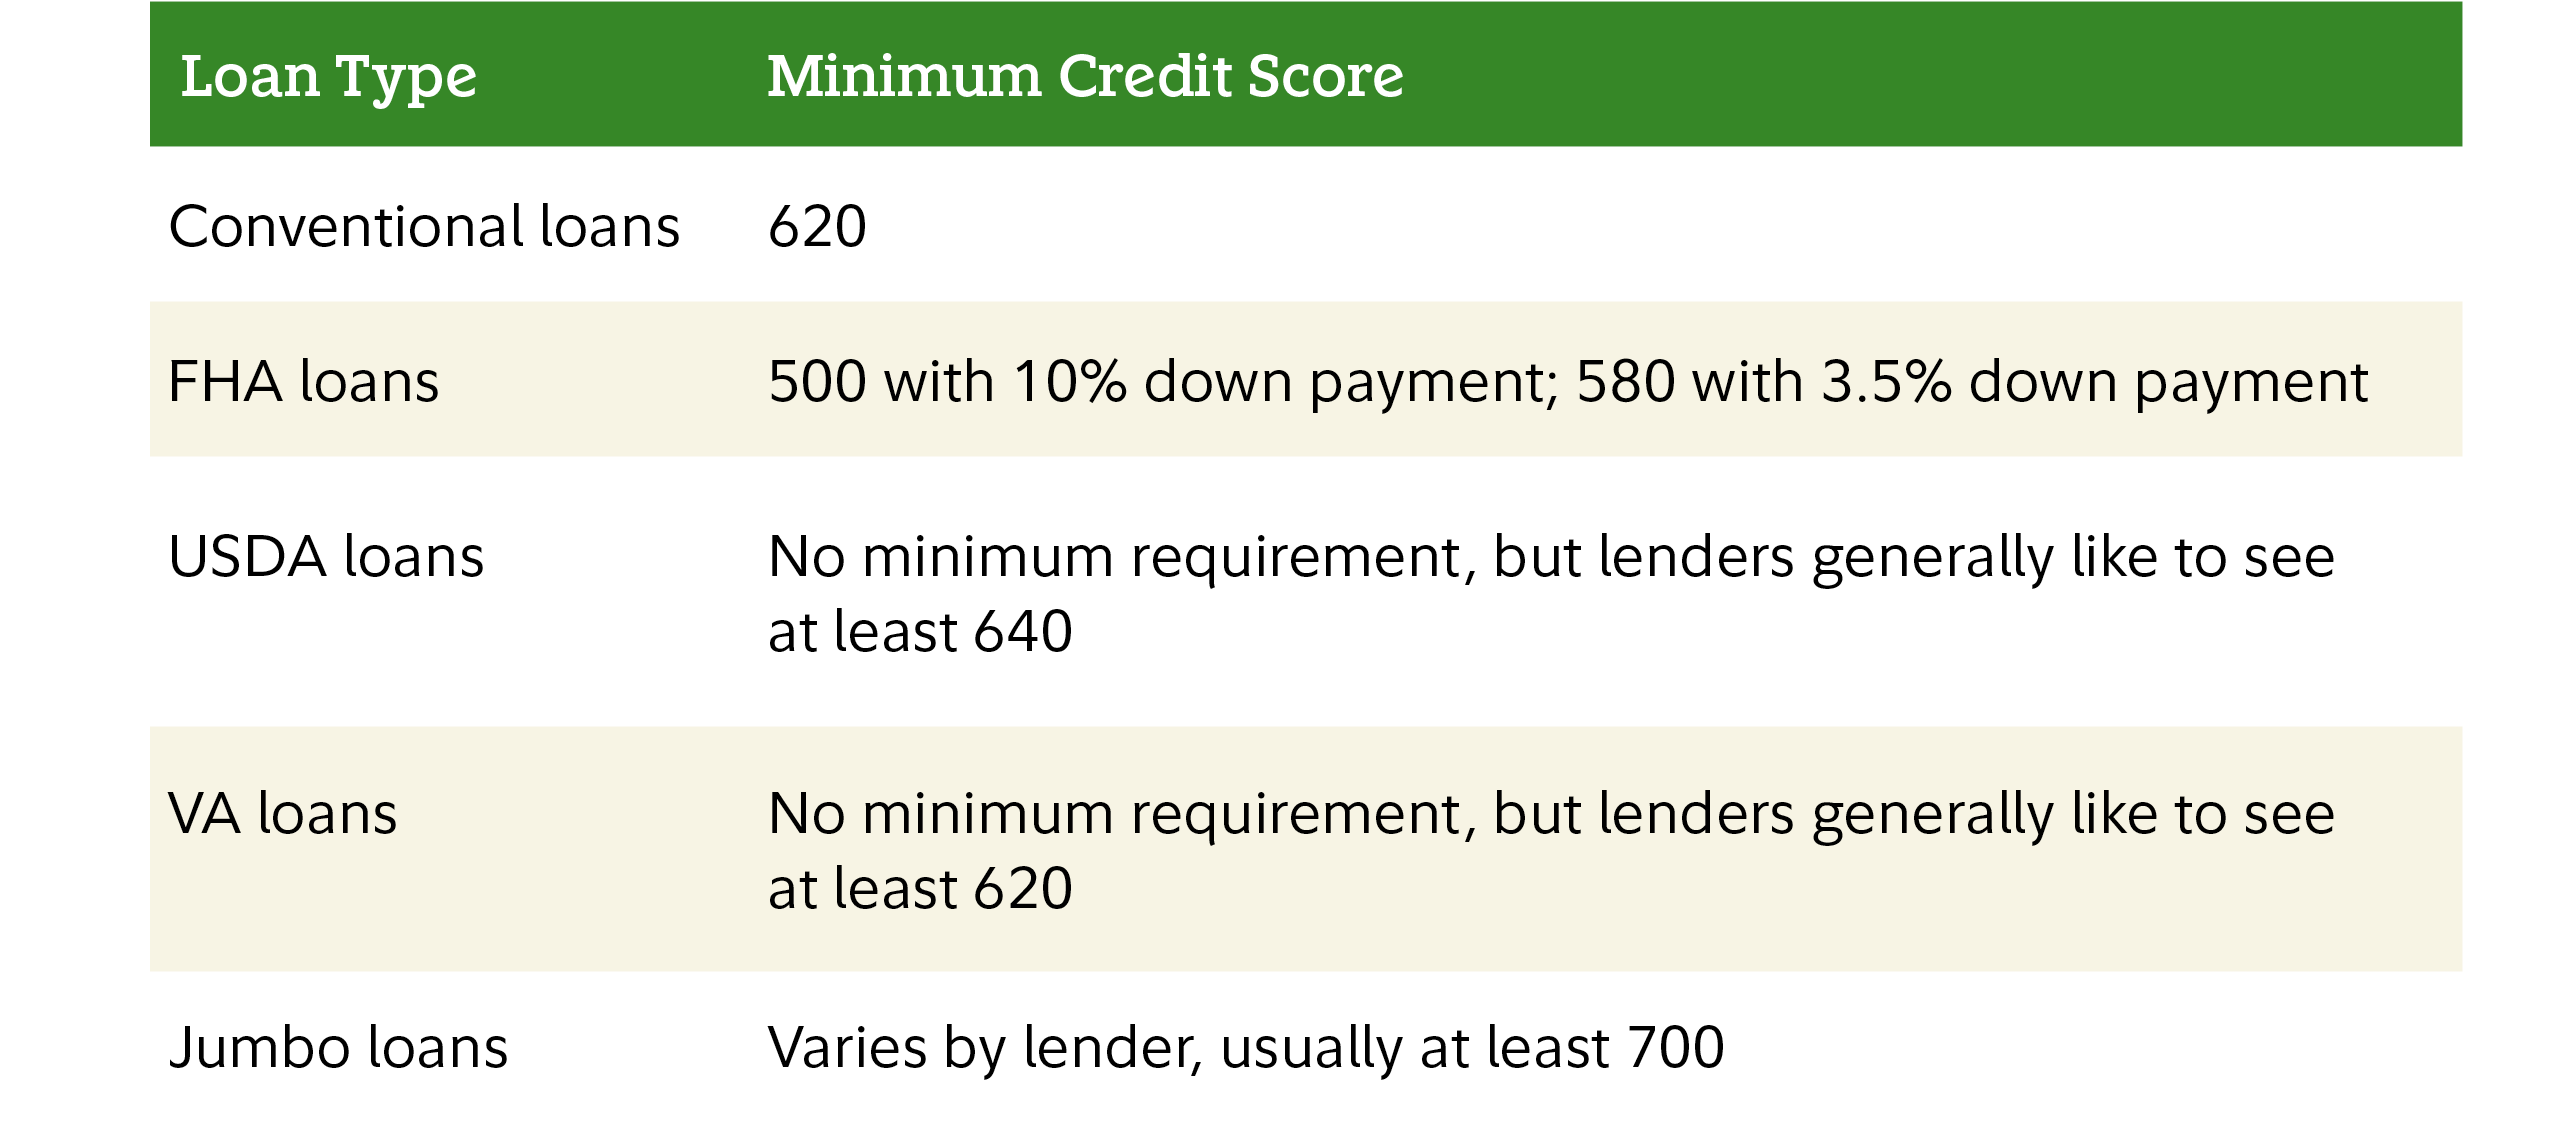
Reviewing your credit health can give you time to dispute errors and pay down debts that could be negatively affecting your credit score, which ultimately affects you when applying for a mortgage. The minimum credit score to be eligible for a mortgage loan depends on both the lender and loan type.
Can you get a mortgage loan without having a credit score?— It's possible. However, there are disadvantages to not having a credit history when applying for a mortgage loan. To a name few, there's the potential of having to put down more as a down payment and not qualifying for beneficial programs.
Nevertheless, although time consuming, manual underwriting is possible if you have limited, poor, or no credit score or history. However, your financial history will still be reviewed to determine your mortgage loan eligibility. Some mortgage loans that allow no credit scores are FHA loans, VA and USDA loans, and other specialty lenders. Having a good credit score coupled with established credit can very well improve the likelihood of you qualifying for a mortgage (with a more favorable interest rate); but again, it's possible to secure a mortgage loan with limited, poor, or no credit score or history.
Your debt-to-income ratio
Debt-to-income (DTI) is what lenders use to measure the amount of debt you have against your overall income—it's a numerical measurement of your financial health and creditworthiness. It takes into account your credit card payments, student loan payments, and any/all other payment obligations. Your DTI helps lenders determine the probability that you'll be able to make monthly payments on a mortgage loan.
If your monthly debt is high compared to your gross monthly income, then it's likely that your DTI is high. Generally, lenders prefer to see a low DTI ratio (typically 36%); however, having a higher DTI doesn't necessarily mean you won't qualify for a mortgage loan. To add, your DTI could also affect the interest rate you receive, with higher DTI ratios getting a higher interest rate, in comparison to lower DTI with lower interest rates.
Your documents
- Employment Lenders generally look for stable and continuous employment and is viewed as favorable. When applying for a mortgage loan, you'll need to verify your employment and may need to provide your previous employment history.
- Down payment The upfront portion of a home's price that will be paid out of pocket, depending on how much, can reduce the lender's risk, determine what mortgage loan you qualify for, and possibly lower your interest rate. Also, if you’re using money received as a gift for a down payment, you’ll probably need to show documentation of the source.
- Proof of income pertains to documents (that are often needed) that show how much money you make. Common examples are pay stubs from the most recent two months, W2 forms for the past 2 years, business tax returns (for business owners), and1099 forms (if you're a contract employee).
- Asset statements relate to financial documents that list your money, property, and valuables. Common examples are checking and saving account statements, retirement account and business accounts.
- Valid photo ID
- Social security card
- Recent residential addresses
- Balance letter (if using gift funds)
- Bankruptcy documents (if any)
- Bank statements