

Traditionally, cryptocurrency taxes have often been difficult to calculate. However, thanks to the IRS’s 1099-DA tax form, which reports digital asset proceeds from cryptocurrency broker transactions, the process got a little easier.
How does it work? If you sold crypto this tax year, read on.
What is a 1099-DA tax form?
The 1099-DA is a tax form that reports gross proceeds from the sale or exchange of digital assets (like bitcoin, ethereum, NFTs, and stablecoins) through cryptocurrency brokers. You might be familiar with other 1099 tax forms for different types of investments. This is similar, but for crypto.
Who receives a 1099-DA form?
You’ll get a 1099-DA form if you sold digital assets with a cryptocurrency broker this tax year. Your broker is required to report it to both you and the IRS.
If you used multiple brokerage platforms to trade crypto this tax year, you’ll get multiple 1099-DA forms (one statement per account) and note that each form may list multiple transactions. These forms will be sent to you by the cryptocurrency broker(s) by mid-February.
What’s included on a 1099-DA?
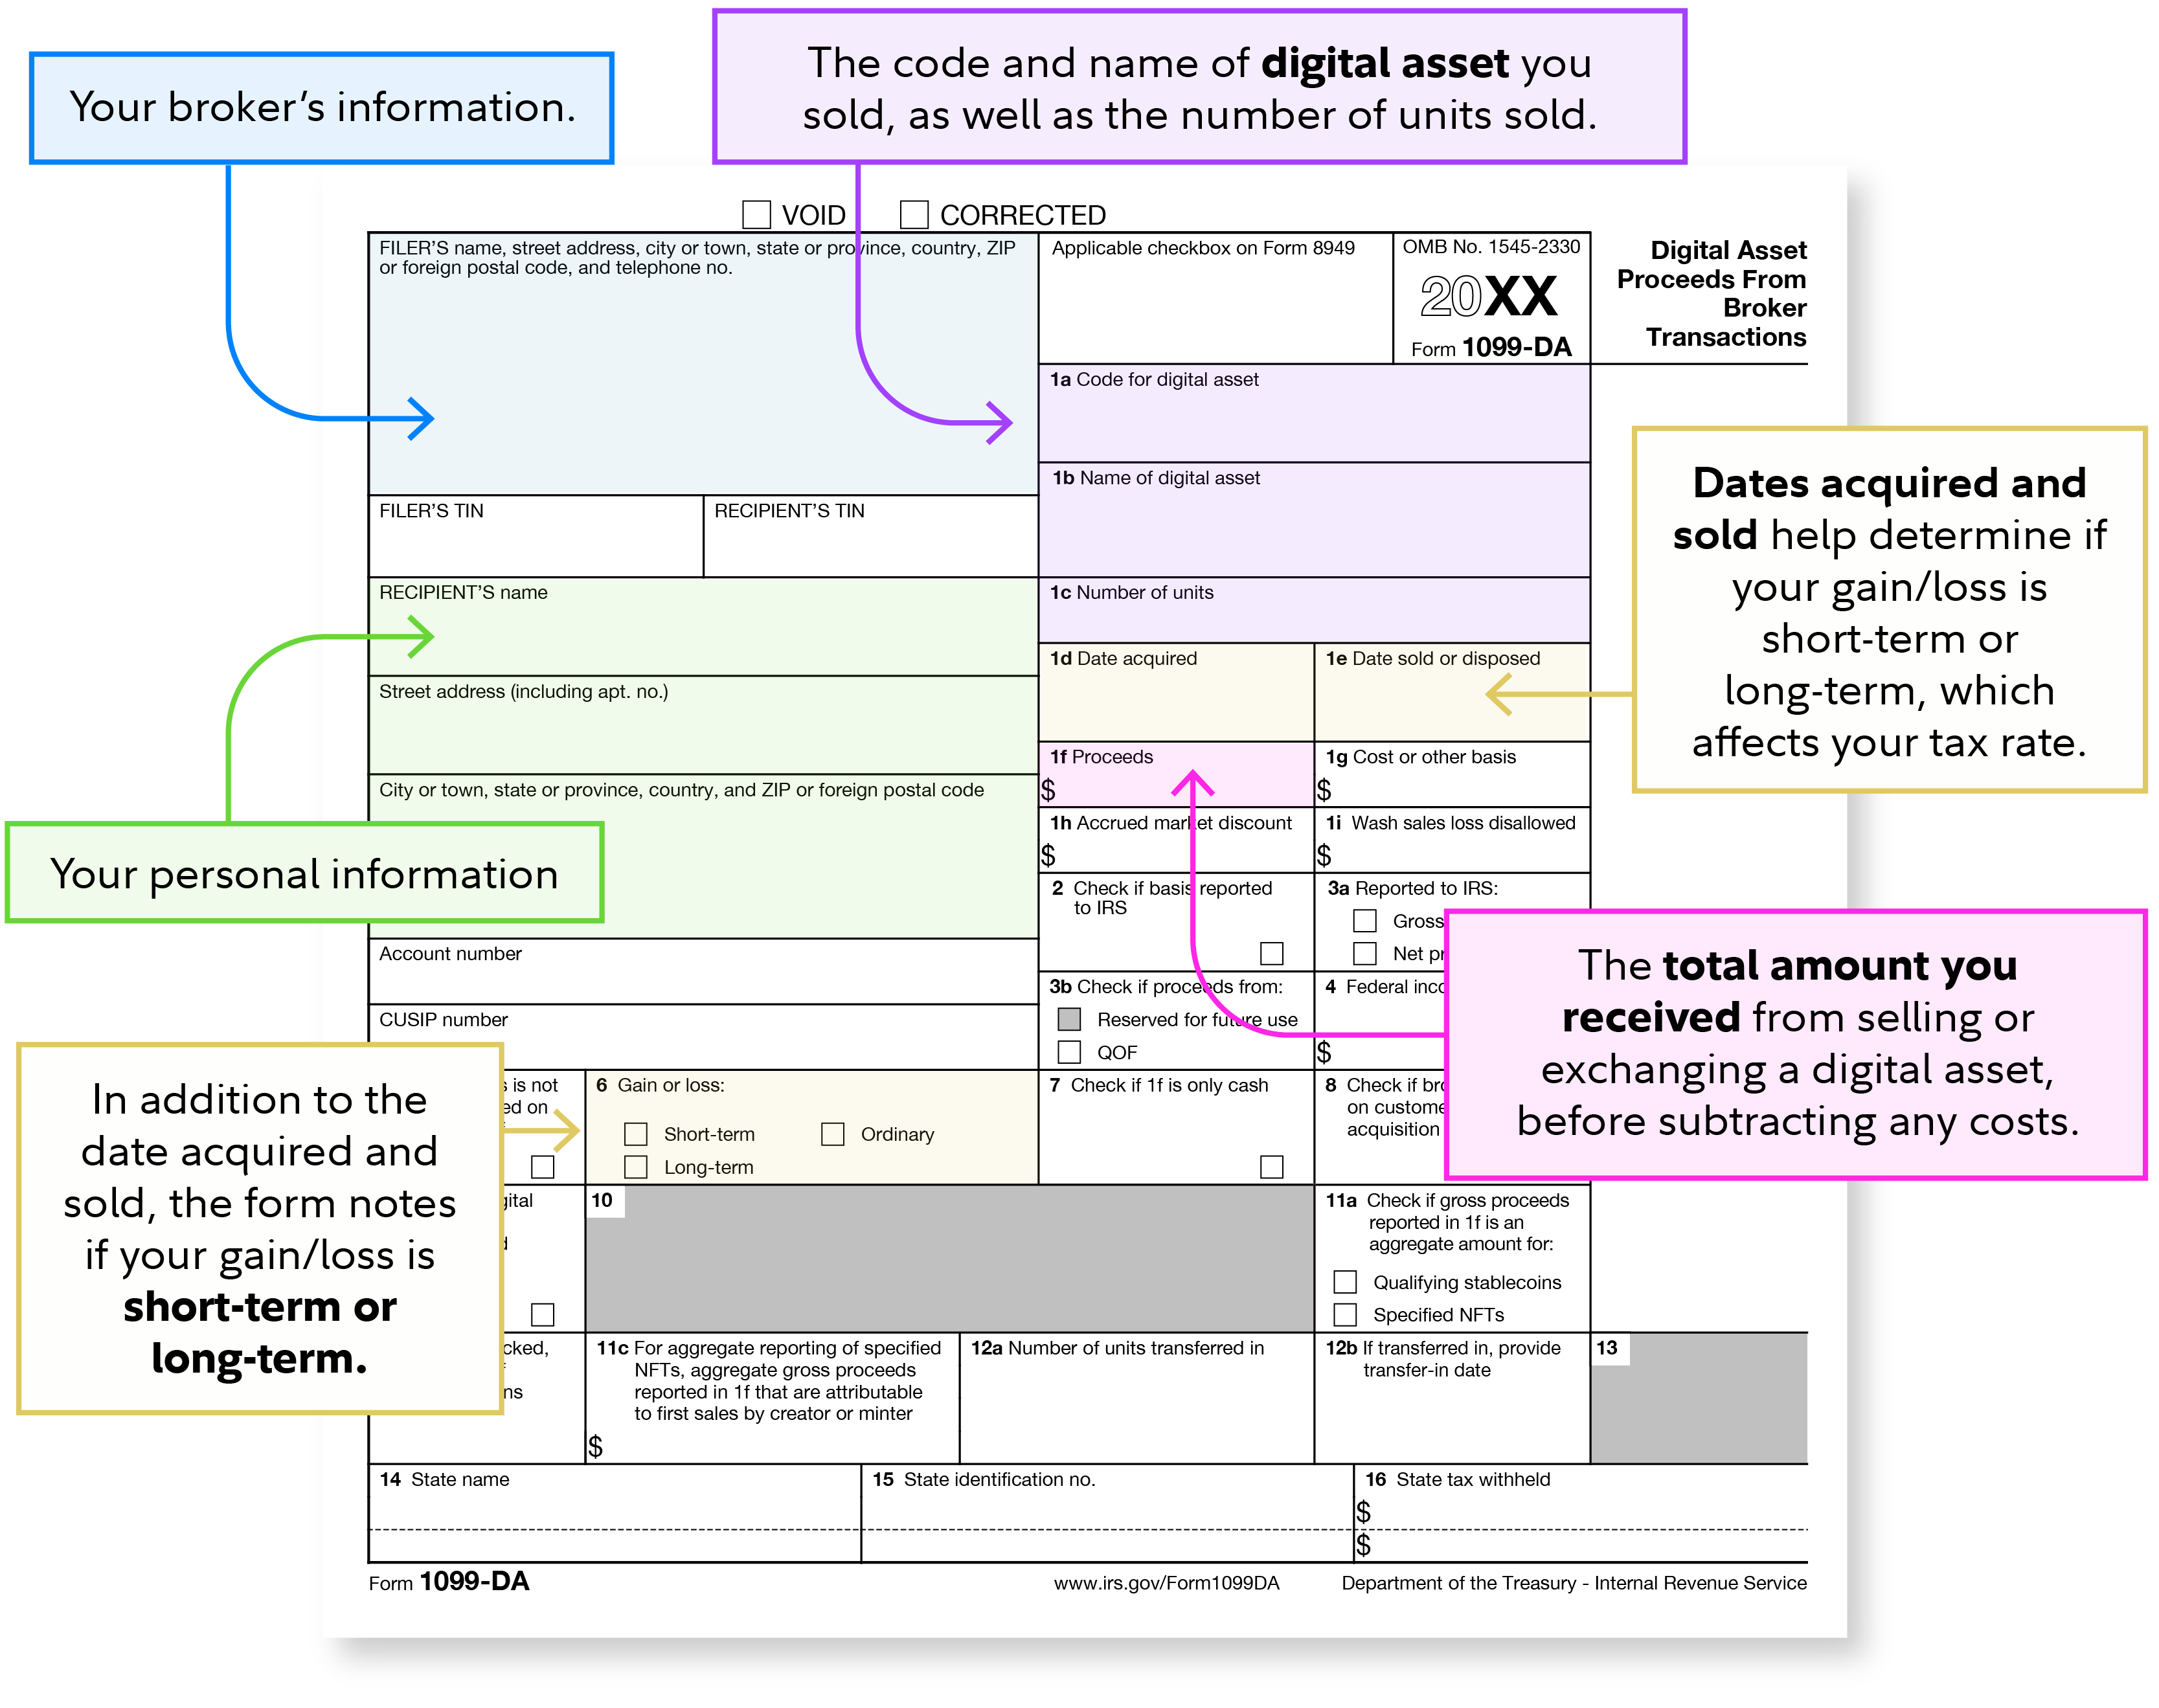
In your 1099-DA form, you’ll see your cryptocurrency broker’s information, the code and name of the digital asset you sold (and number of units sold), your personal information, and more (see an example of a 1099-DA below).
What’s not reported to the IRS on a 1099-DA?
Cost basis (the price you originally paid for your crypto, plus any additional fees–like brokerage fees and commissions) is subject to different reporting rules depending on how and when your digital assets were acquired. For crypto purchased through a cryptocurrency broker beginning in 2026, cost basis information may be reported to the IRS. However, cost basis for certain transferred crypto assets or older holdings may not be reported to the IRS, even if that information appears on your copy of Form 1099-DA. Because reporting requirements vary, it's important to review your records and verify that your cost basis information is accurate before filing your tax return.
If you sold crypto over the past year, it’s still important to review your cost basis and gain/loss calculations and ensure accuracy even if this information isn’t being reported to the IRS.
For reference, gain/loss = sale price – purchase price.
- If the result is positive, that’s a capital gain.
- If the result is negative, it’s a capital loss.
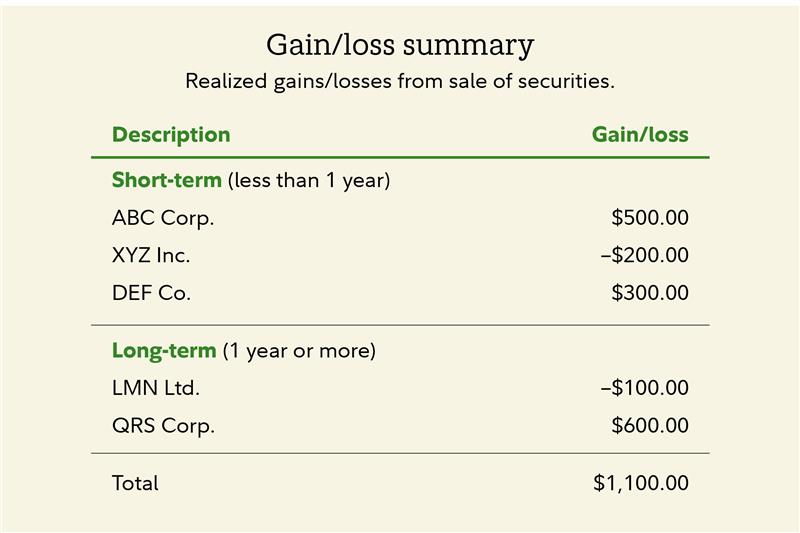
Fidelity Crypto® customers receive gain/loss calculations with their 1099-DA. If your platform doesn’t provide one in the 1099-DA forms, you’ll have to calculate it separately. Check out an example Gain/Loss Summary below.
Why does a 1099-DA matter?
Form 1099-DA matters because it’s the first IRS form specifically for digital assets like crypto and NFTs. It helps both taxpayers and the IRS by:
- Creating a standard way to report crypto sales, similar to how stock trades are reported on Form 1099-B.
- Making sure both you and the IRS get the same info from cryptocurrency brokers, which helps prevent mistakes or missing income.
- Helping you file taxes more easily by showing key details like how much money you made from selling crypto (but remember, you need to calculate gains/losses separately).
What should I do when I get my 1099-DA form?
When you receive your 1099-DA form, here are a few steps to take next:
- Review the form for accuracy: Check that your name, transaction details (like asset type and sale amount), and other information are correct. Report any errors to the cryptocurrency broker that issued it.
- Gather your cost basis records: Review any cost basis reported on your 1099-DA, and compare this with your own records. If you’re a Fidelity Crypto® customer, you can find this information readily available in your Gain/Loss Summary form.
- Share the form and your gain/loss summary with your accountant: Your tax advisor will use both the 1099-DA and your transaction history to complete your tax return accurately.
Additional considerations
Some cryptocurrency brokers let you pick which specific crypto purchase (or “lot”) you want to sell, which can help with tax planning. With Fidelity Crypto®, if you don’t choose a specific lot before selling, Fidelity Digital Assets® will use the FIFO method (first in, first out) meaning the oldest crypto you bought will be sold first.
It’s also always important to remember to practice detailed recordkeeping.
That starts with understanding what is and isn’t a potentially taxable event with crypto. You can find more information on potentially taxable events in our crypto tax guide.
Also, remember that learning basic crypto tax information may help you keep more of your profits. To avoid any unexpected surprises, always know how your trade will be taxed before you execute. And it’s important to note that Fidelity doesn’t offer tax advice, so be sure to consult a tax advisor about your specific situation.