

Maybe your choice of where to live is determined by dreams of beaches, mountains, and sun-filled days. But choosing where to live may also depend on practical things, such as access to work and housing, even taxes.
In fact, the tax rate of a particular state can have a major impact on your after-tax income and can contribute significantly to costs. Simply put, states with higher individual tax rates may reduce your income more dramatically than states with lower tax rates and states with no income taxes.
So it's no surprise low- or no-income-tax Sun Belt states continue to see population growth, even as the pandemic-era exodus from higher-tax states in the Northeast and West Coast appears to be tapering off, according to the most recent data from the US Census Bureau. For example, no-income-tax Florida gained more than 197,000 residents while Texas gained 391,243 inhabitants from 2024 to 2025. Meanwhile, high-income-tax California lost 9,465 people, continuing a multi-year trend of population decrease, while New York's gain of 1,008 residents continues several years of modest population growth following pandemic-era declines.
The population data suggests that state income taxes are not the only force driving people from one region to another. But if you are considering relocating, understanding how state income taxes can impact your bank account—or portfolio—after taxes is key to making your hard-earned money go further.
What are the lowest income tax states?
At the top of the list are the 9 states with no state earned income tax: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. That's not to say these are no-tax states. Many make up revenues with higher property taxes, sales tax, and other taxes and fees.
But particularly if you are a high-income earner, the tax savings of moving to a lower or no-income-tax state can add up. Imagine you have $250,000 in earned income as a single filer in Vermont. Fidelity has calculated your effective state tax rate, or the percentage of your total income you pay toward state taxes, as 5.94%. In other words, you would pay approximately $15,000 of your total income to state income taxes. Comparatively, if you were to move to nearby New Hampshire, you would pay no state income tax, which would result in annual tax savings of an equivalent amount.1
Additionally, a hypothetical single person earning $100,000 annually who moved from Oregon, which ranks among the highest-income-tax states for married and single filers, to a no-income-tax state such as Florida or Texas could save approximately $7,000 annually by changing states. On the other hand, someone living in Nevada earning the same amount of money might owe approximately $3,700 more per year simply by moving to nearby Utah, where state tax rates rank among the 21 most expensive for both single and married joint filers with $100,000 of annual income.
The following are the best and worst states for taxes on ordinary income of $100,000 annually. Note: While Washington, DC, is not a state, it is included in our analysis.
10 highest and lowest state tax rates
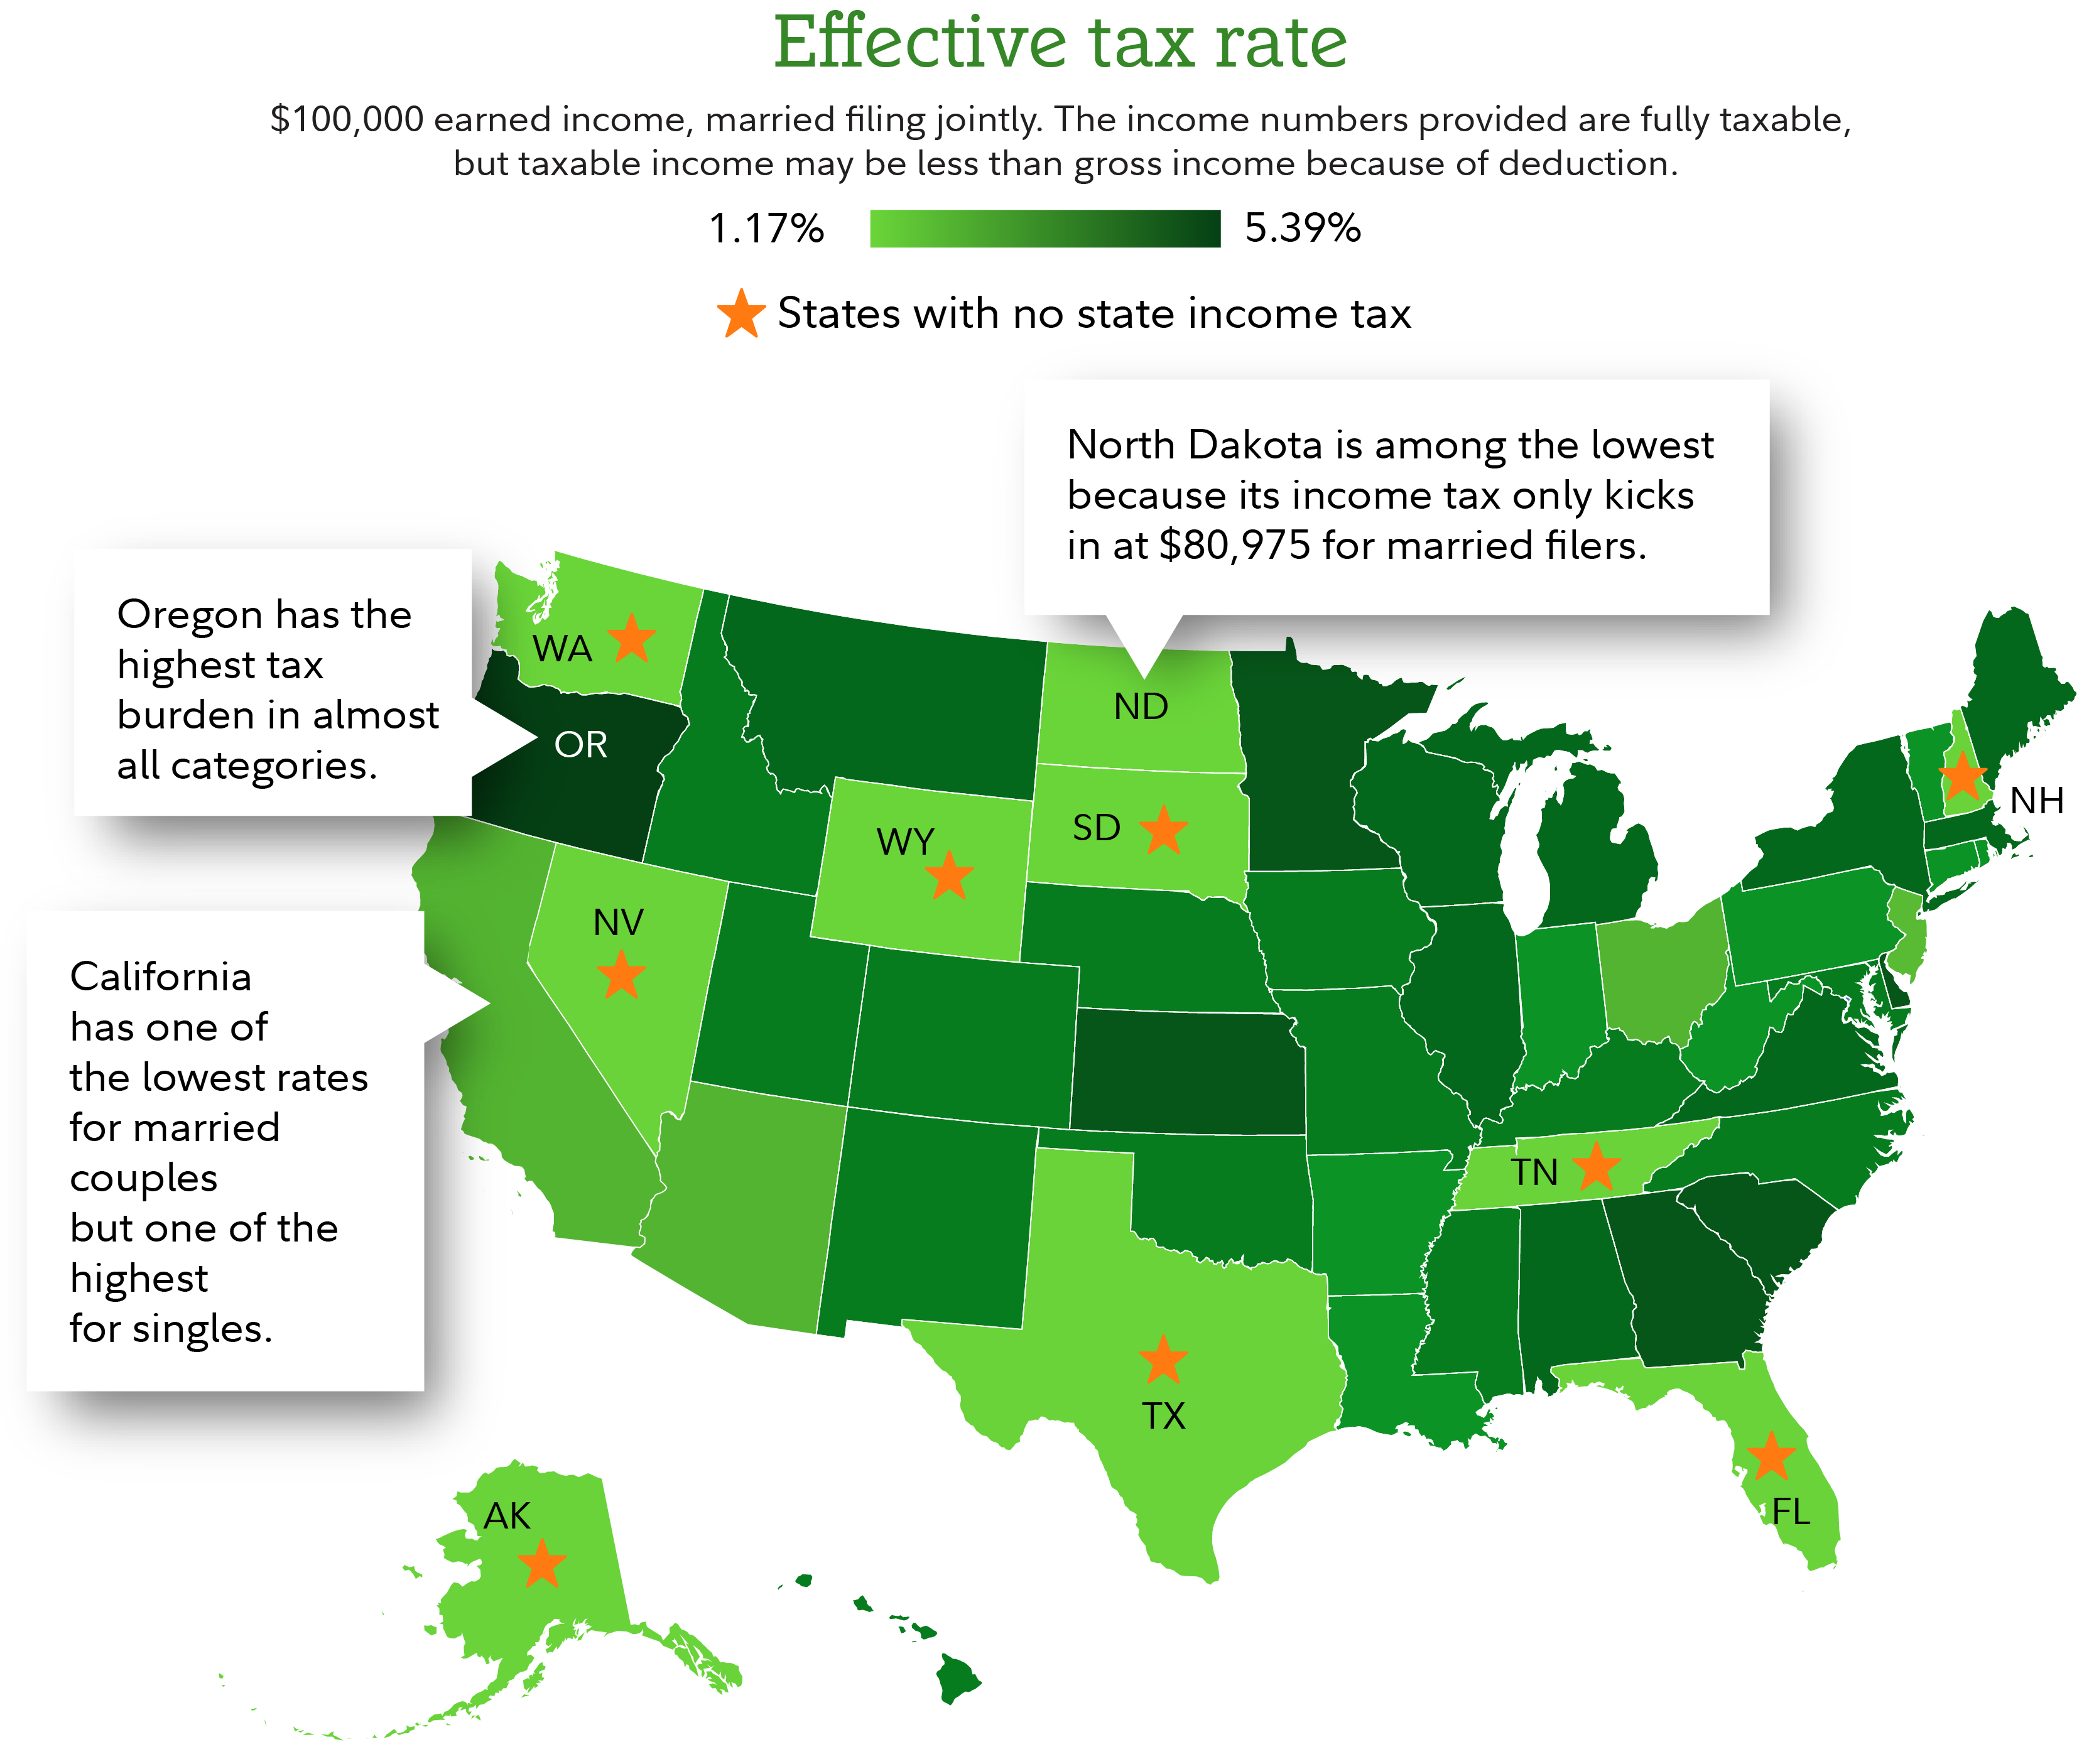
In the graphics below we illustrate the range of those effective income tax rates for both singles and married couples with $100,000 in income. The effective rate—which is different from your marginal tax rate—is the amount of your pay that goes to state income taxes once you’ve factored in deductions and credits.
You may be surprised about some of the best and worst states, depending on your marital status.
Source: Fidelity
Charts assume earned income of $100,000. All income is assumed to be ordinary income subject to income taxation. State income tax brackets are applied. Federal standard deduction based on filing status and age-based exemptions are used in place of state standard deductions and exemptions. No tax credits are assumed. All data is as of 2025. Tax law may have changed since that date.
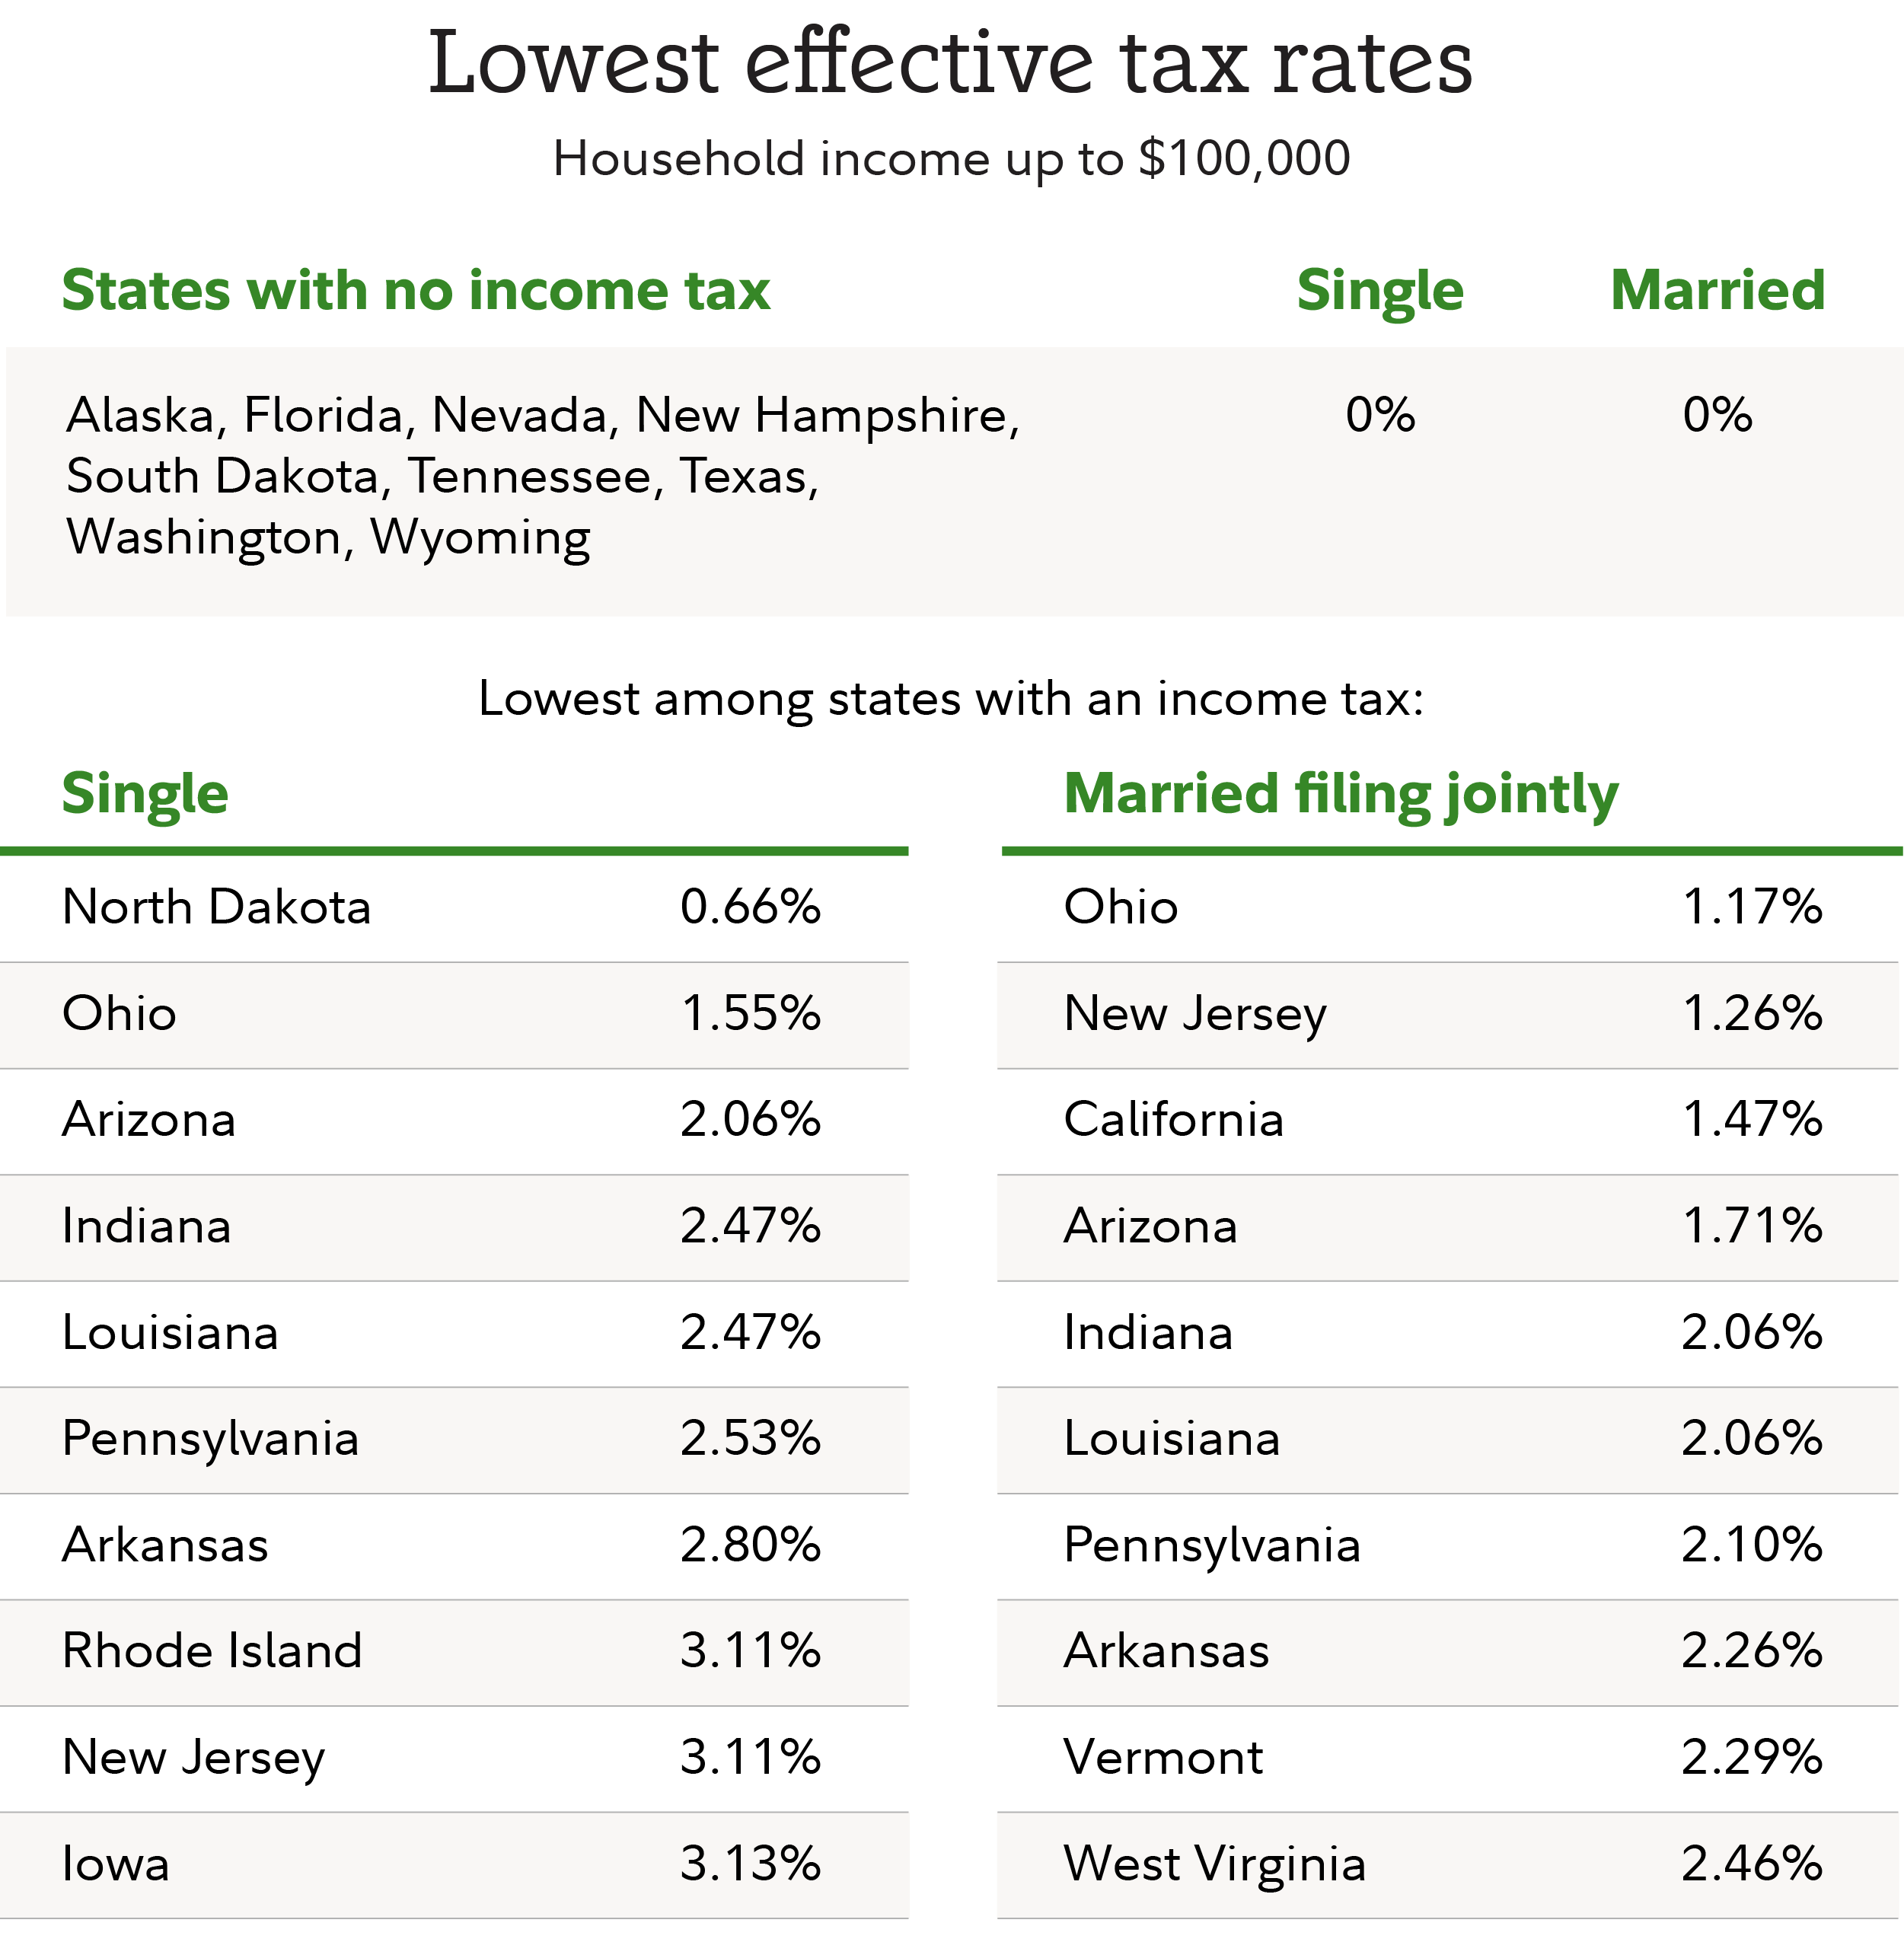
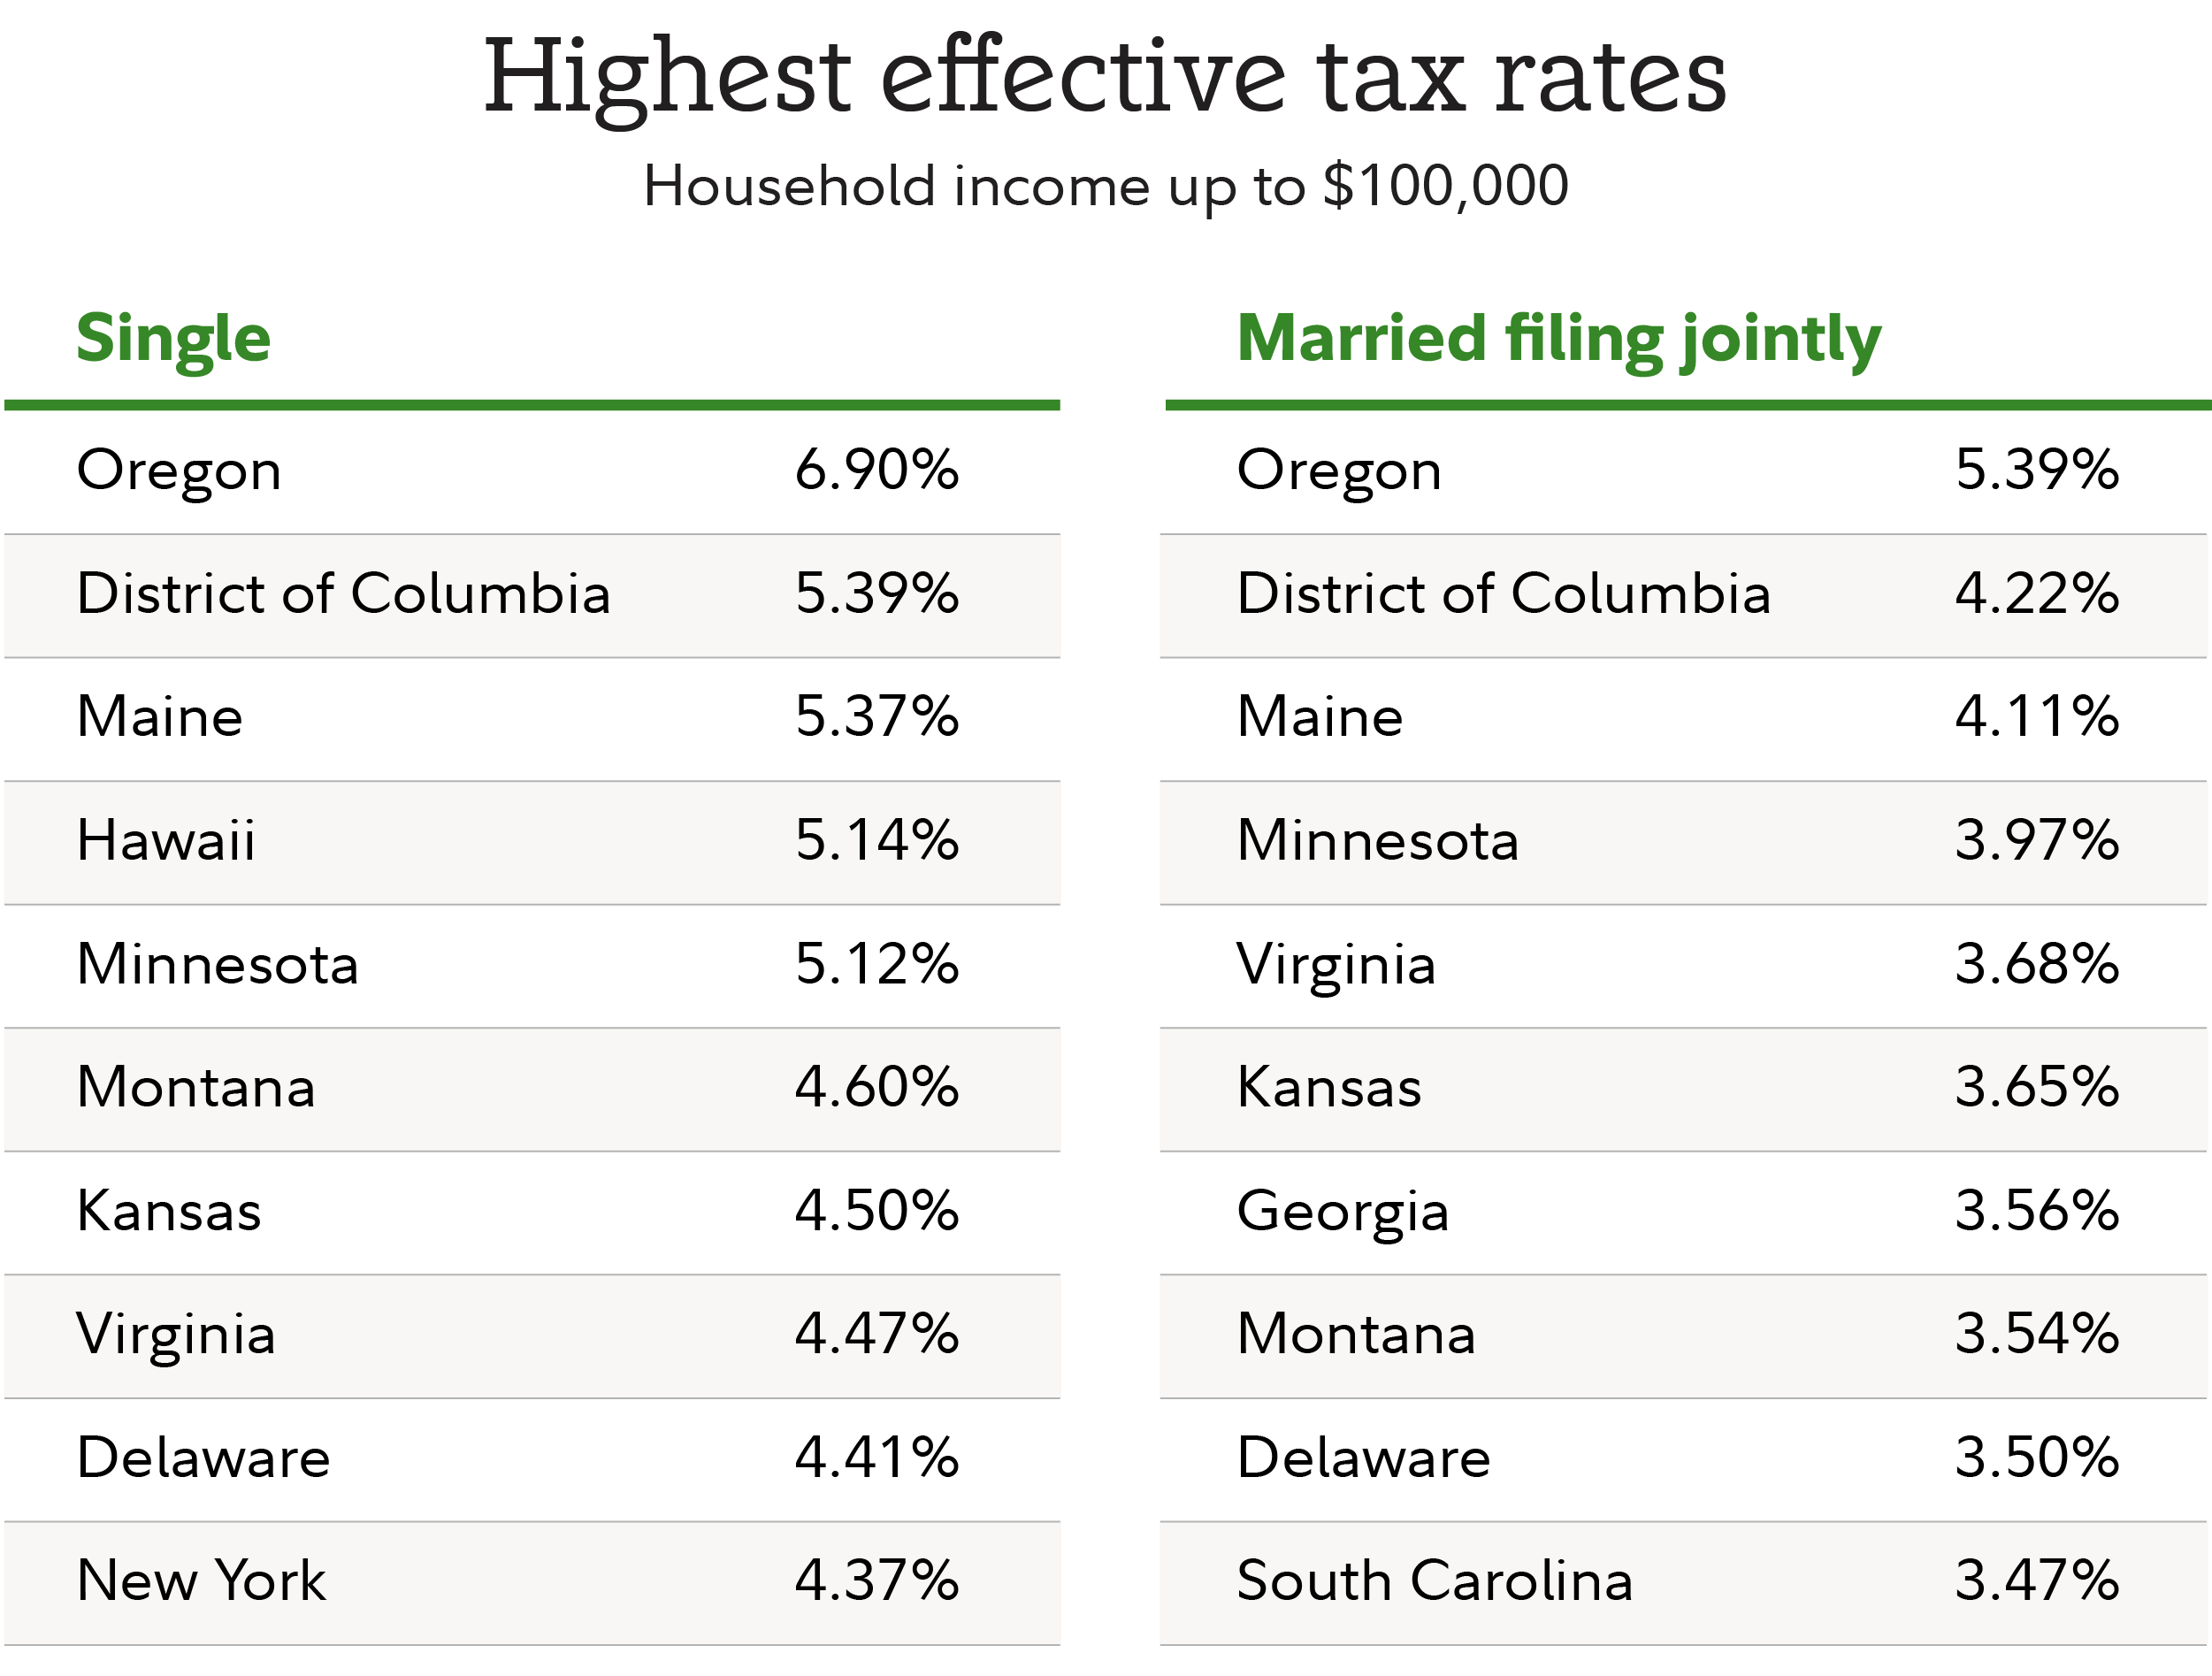
The effective state tax rates for a single filer earning $100,000 of income vary from a high of 6.9% in Oregon to a low of 0% for those with no state income tax. (The low among states that do levy an income tax is 0.66% for North Dakota). For a married couple filing jointly with the same income, the combined effective state income tax rates range from a high of 5.39% in Oregon to a low of 0% for those same 9 states, plus North Dakota.
- While the Northeast has a reputation for having the highest-tax states in the nation, it turns out that Oregon has the highest effective tax rates for both single and married joint filers in the US. Hawaii comes in fourth, with a top rate of 5.14% for single filers, and 3.11% for married filers.
- Maine, Minnesota, Virginia, Kansas, Montana, and Washington, DC, are also in the 10 highest-tax states for income tax rates for both kinds of filers.
- While California ranked among the most expensive states for single filers earning $100,000, with an effective tax rate of 4.09%, it also ranked among the 15 best states for married filers at the same income level, with an effective tax rate of 1.47%.
- Ohio, New Jersey, and Arizona are among the states with the lowest effective tax rates for married filers.
- Oklahoma is nearly in the middle for all states for married couples filing jointly and single filers alike.
Source: Fidelity
Charts assume earned income of $100,000. All income is assumed to be ordinary income subject to income taxation. State income tax brackets are applied. Federal standard deduction based on filing status and age-based exemptions are used in place of state standard deductions and exemptions. No tax credits are assumed. All data is as of 2025. Tax law may have changed since that date.
So if you're looking to save money on taxes and your annual income is $100,000 or less, you might consider Florida and Texas despite their relatively high cost of living. But there's always North Dakota and Ohio, which also have favorable tax rates. At the same income level, California could be a good choice if you're a married couple filing jointly, especially if the idea of paying some state income tax isn't a deal-breaker. And then there's New Jersey, which ranks in the top 10 lowest-tax states for both single and joint filers for states with an income tax.
Remember, everyone's tax situation is different, and it makes sense to consult with a financial or tax professional for advice.